What’s moving now
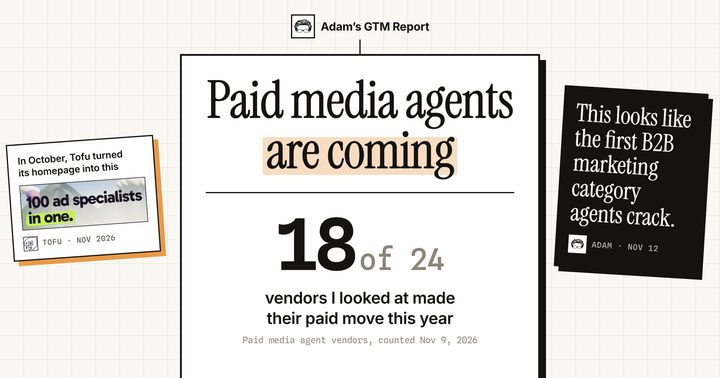 Paid media agents are comingNov 12 · The vendors and builders. Why paid is first. My experiment
 22.6× the usual response · 2,091 engagements
 21.7× the usual response · 7,205 engagements
 X20.6× the usual response · 432 engagements
 10.4× the usual response · 95,461 engagements
 6.0× the usual response · 36 engagements
 BraintrustFirst seen Nov 9Featured roleDirector, AI-Driven Marketing
 IruFirst seen Nov 8Featured roleGTM engineer, Growth & PLG
 LemlistFirst seen Nov 9Featured rolePrincipal, Customer Storytelling & Advocacy
 Cloudflarecurrency unspecified 221,000–304,000 (annual salary) · no family median yetFeatured roleHead of Product Marketing
 BenchlingUSD 208,000–312,000 (annual salary) · at the medianFeatured roleSocial Content Creator
 GorgiasUSD 77,885–101,304 (annual salary) · 45% below the medianTrending Creator
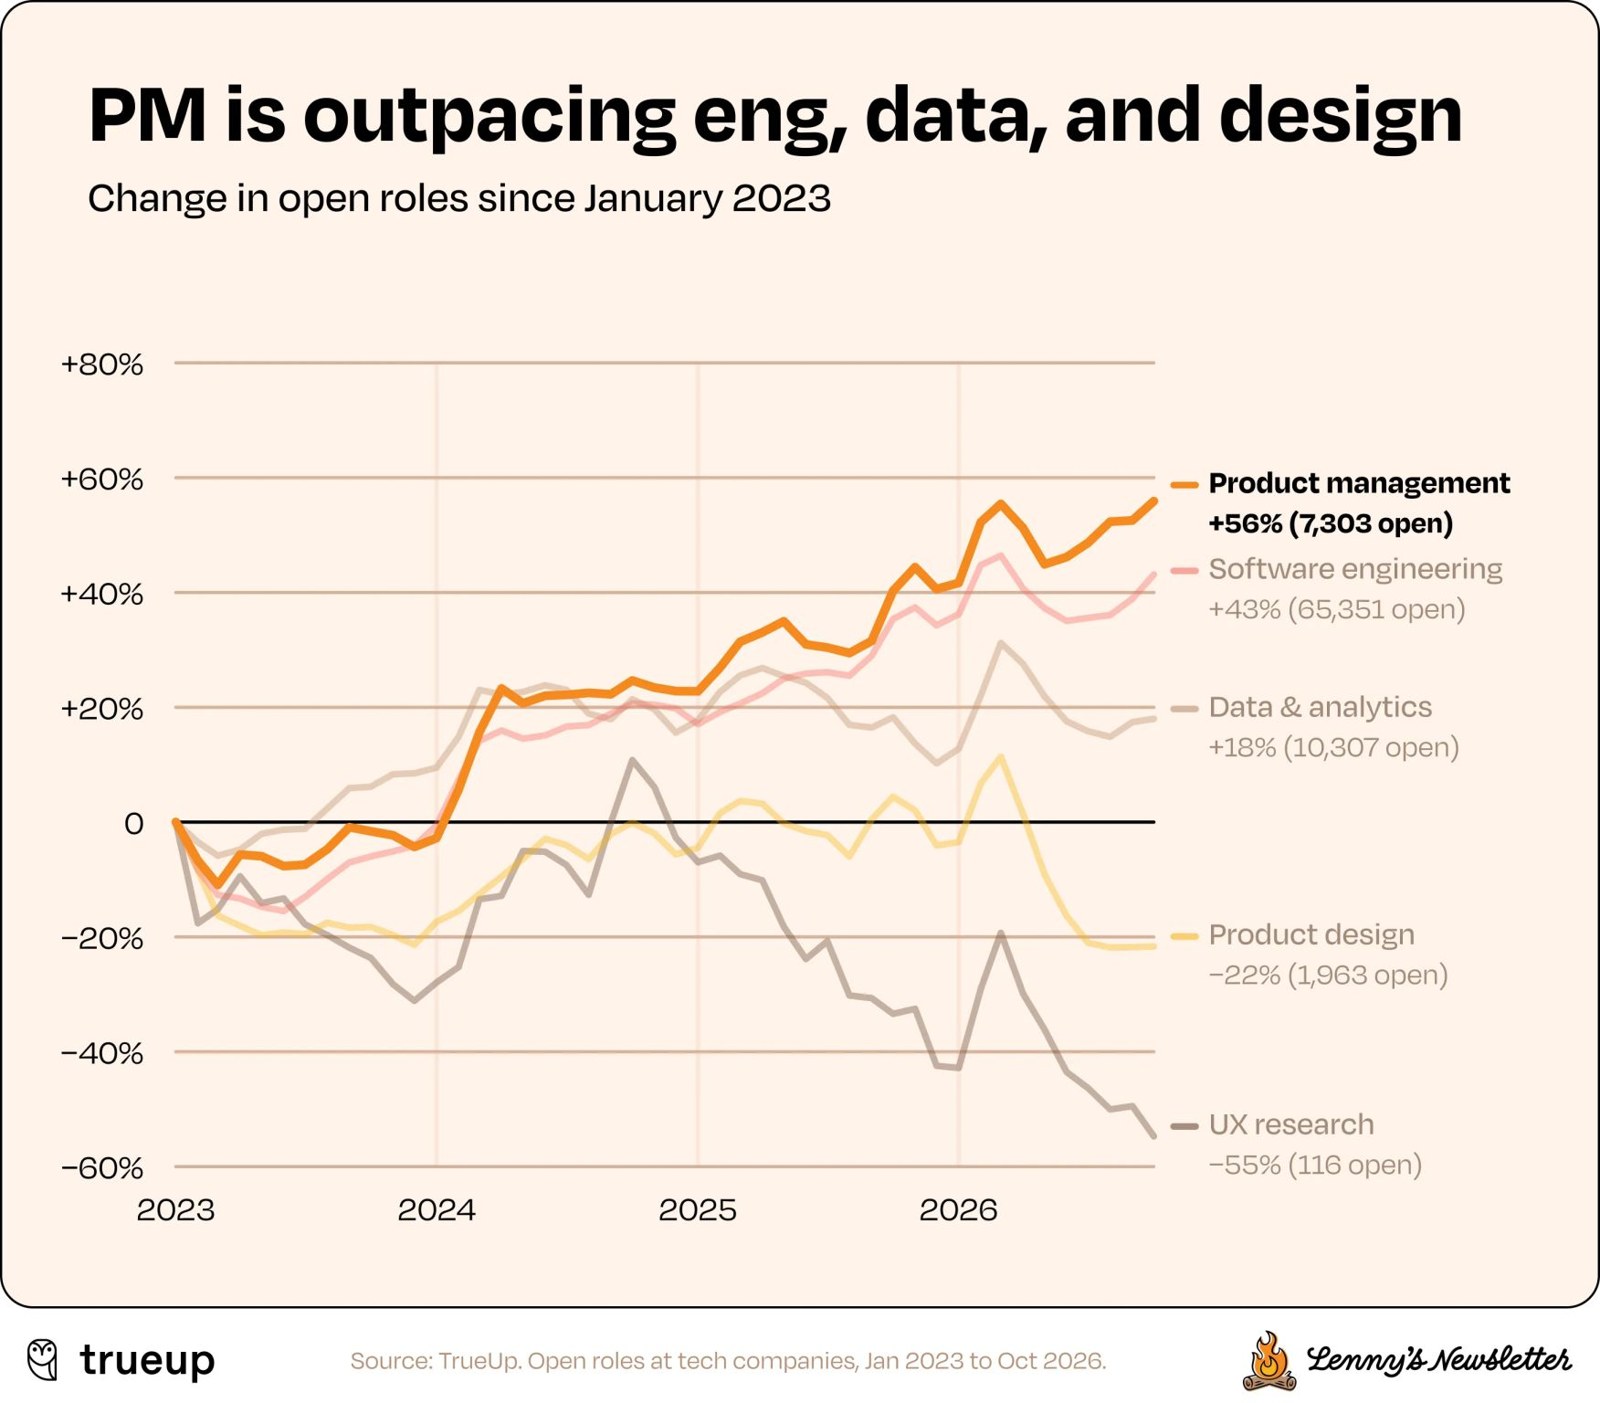
 Lenny RachitskyArgues product managers are benefiting from AI, citing openings up 75% from March 2023 lows and faster growth than other core product roles.
 1,114 interactions · 1d agoTrending Creator
 Elena VernaArgues more women should build AI software and shape whom it serves, citing this aim as the reason for creating SheBuilds at Lovable.
 1,084 interactions · 2d agoTrending Creator
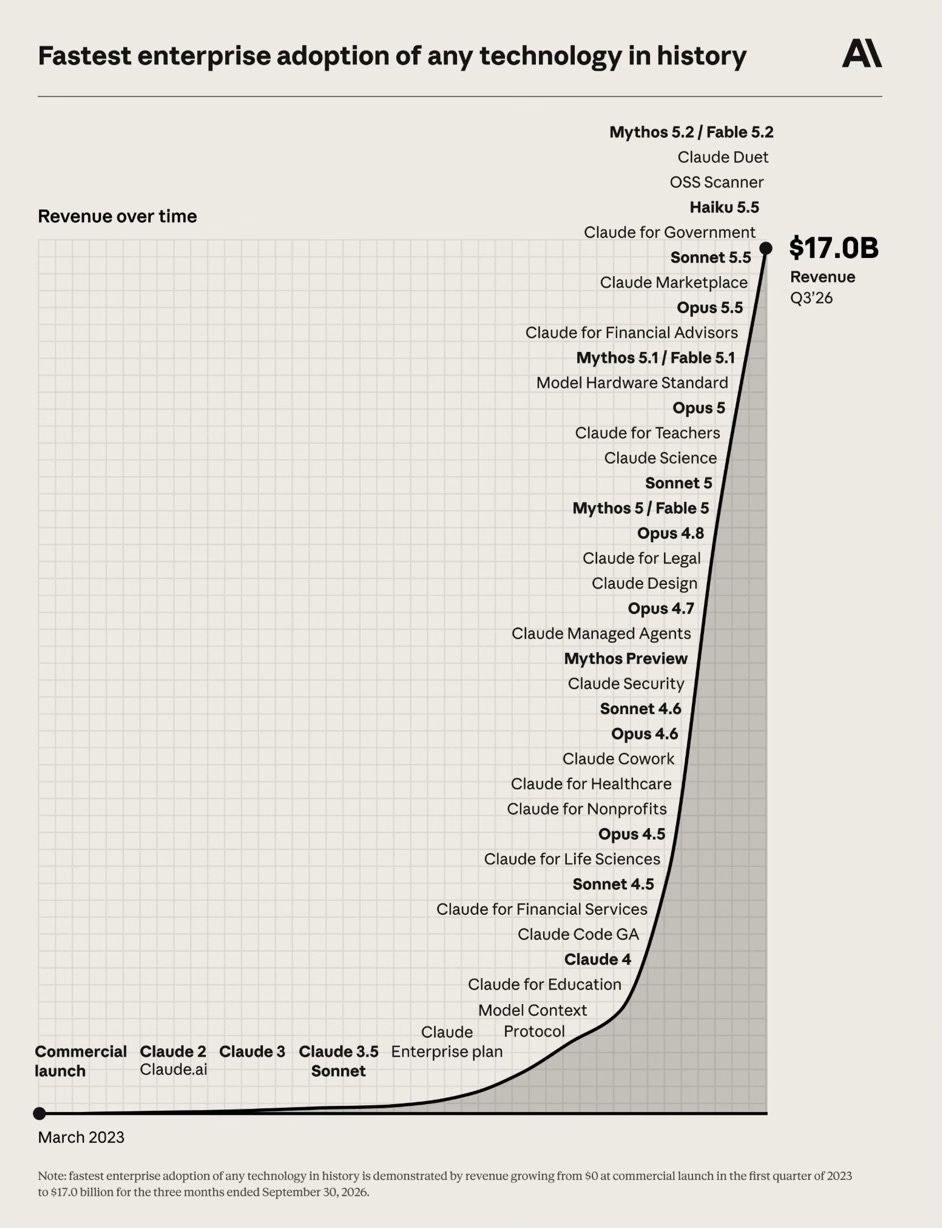
 Peter WalkerCites Anthropic’s claimed growth to $17 billion per quarter in 3.5 years and argues public trading would help settle valuation disputes.
 561 interactions · 2d agoTrending Creator
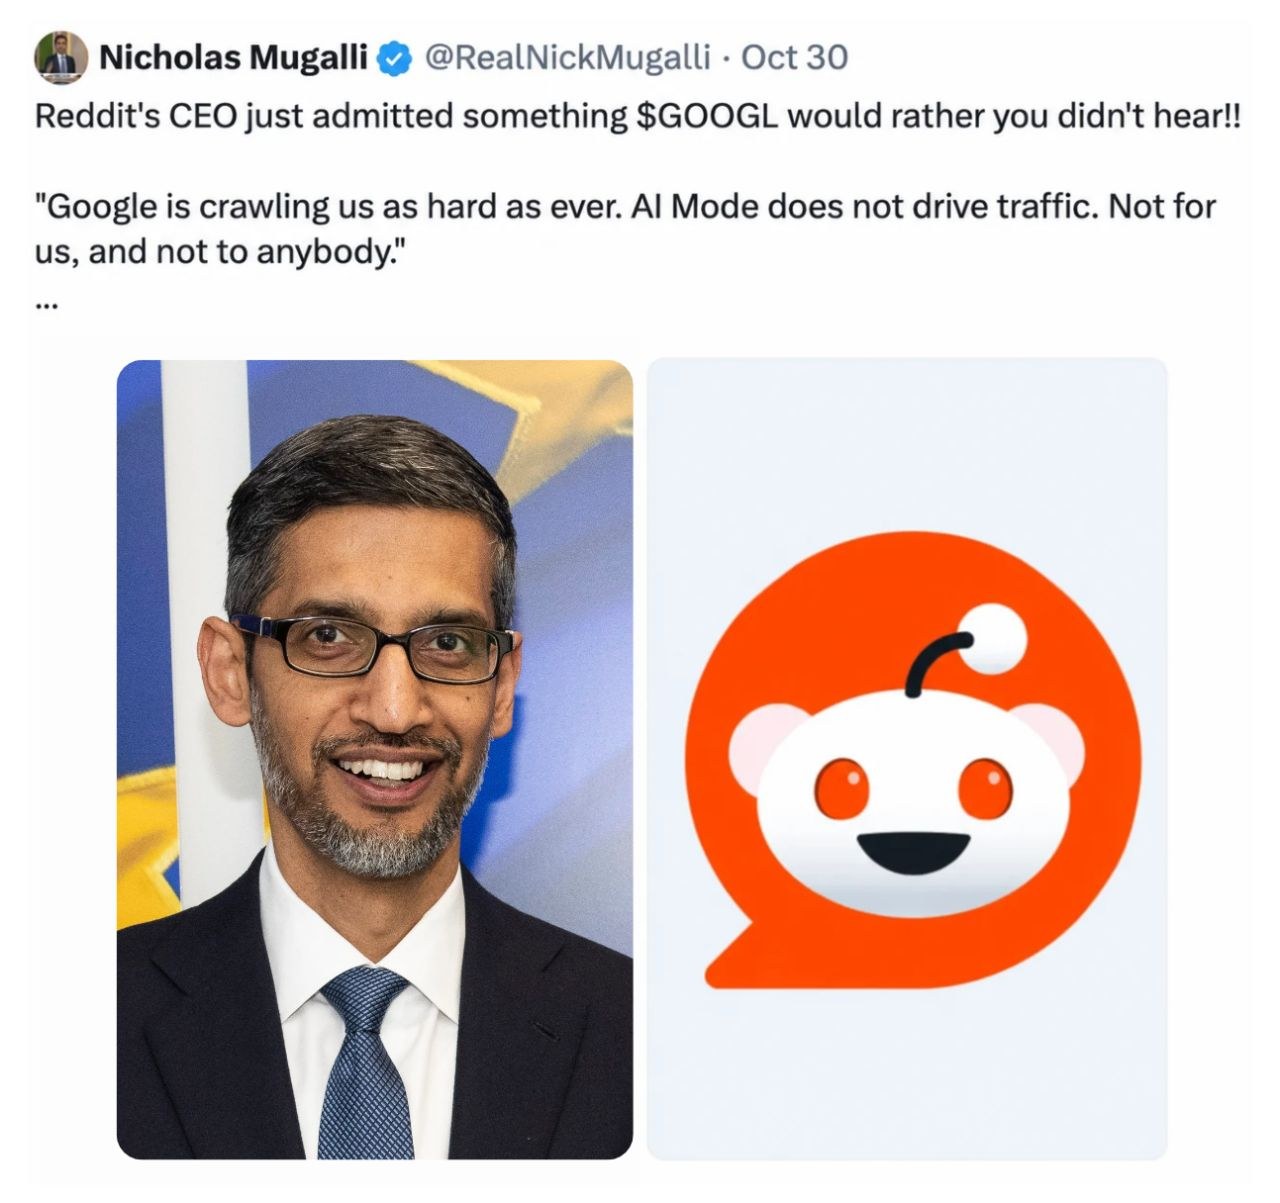
 Ross SimmondsCiting Reddit’s reported lack of traffic from Google AI Mode, the author recommends prioritizing AI mentions, Reddit participation, and inclusion on third-party pages in SaaS marketing plans.
 467 interactions · 2d agoTrending Creator
 Nick PalaszArgues failed AI outbound campaigns need better customer targeting, compelling messaging, and proven campaigns before automation, rather than additional tools.
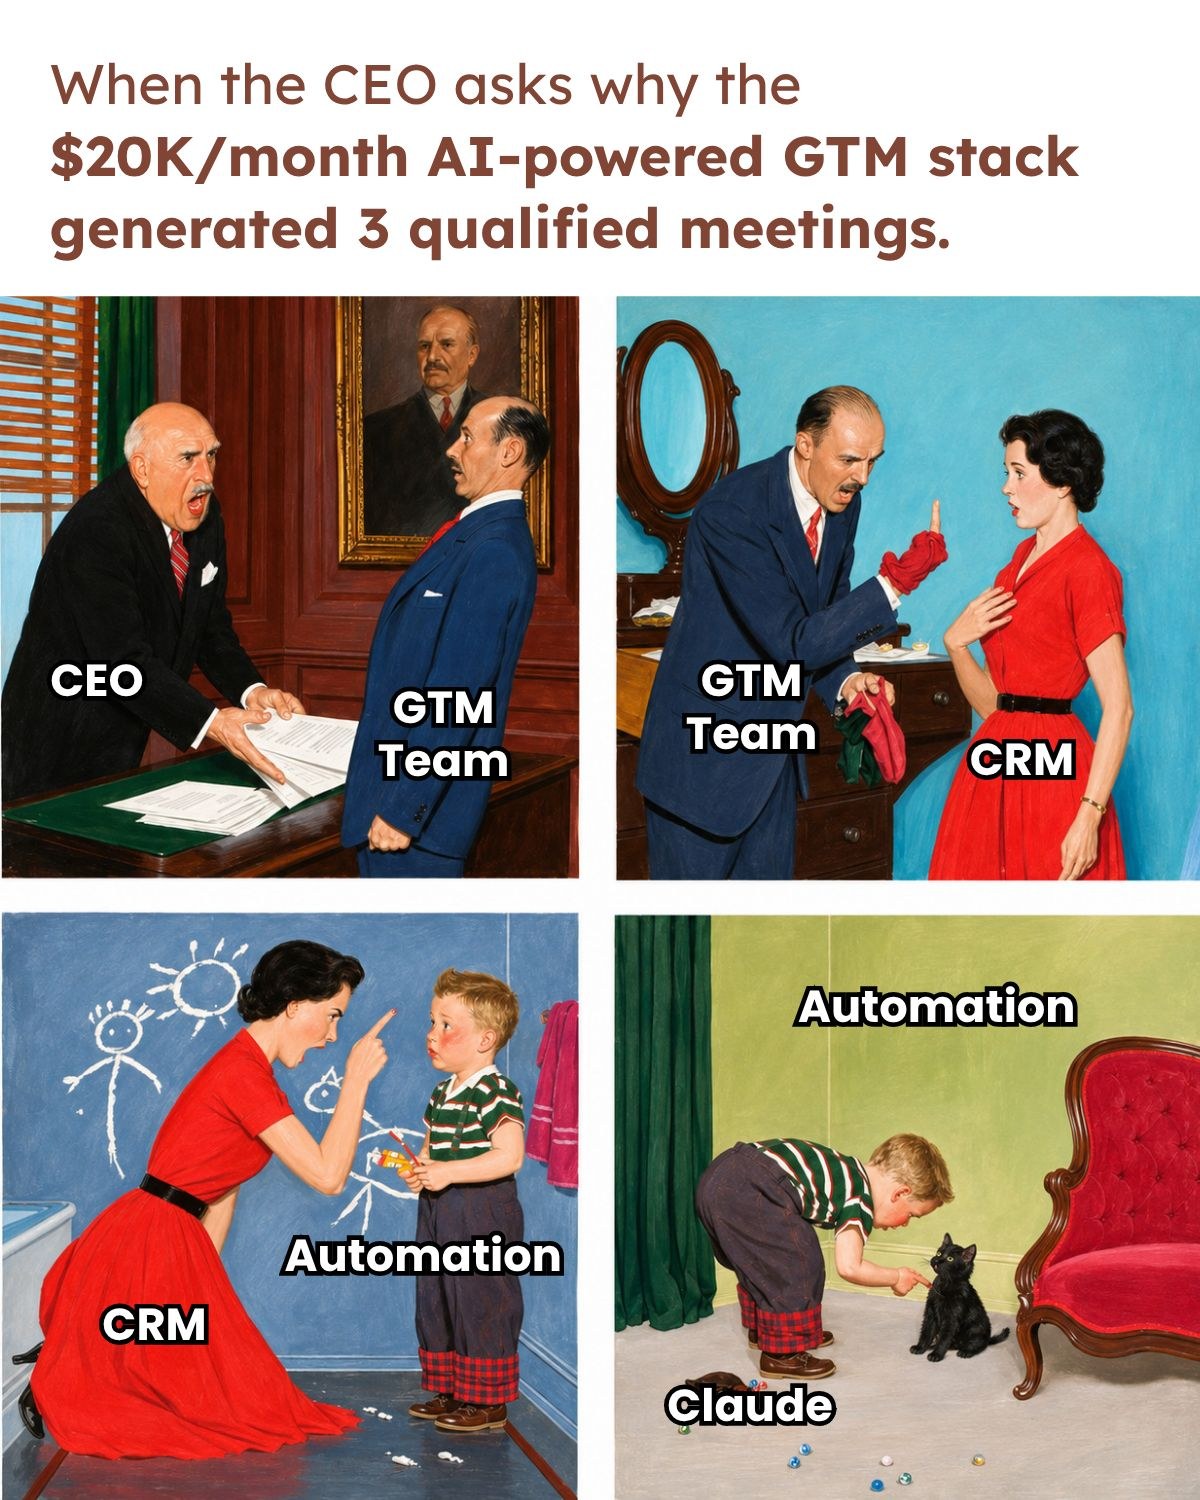 456 interactions · 2d agoTrending Creator
 Mark JungRecommends scoring older content for accuracy and relevance, then revisiting changed assumptions to generate fresh ideas while maintaining a consistent subject focus.
 425 interactions · 2d agoTrending Creator
 Kevin IndigReports ChatGPT’s Business Hub offers 28-day website-linked mention, citation, and click analytics, but lacks individual prompts, competitive benchmarks, and documented revenue attribution.
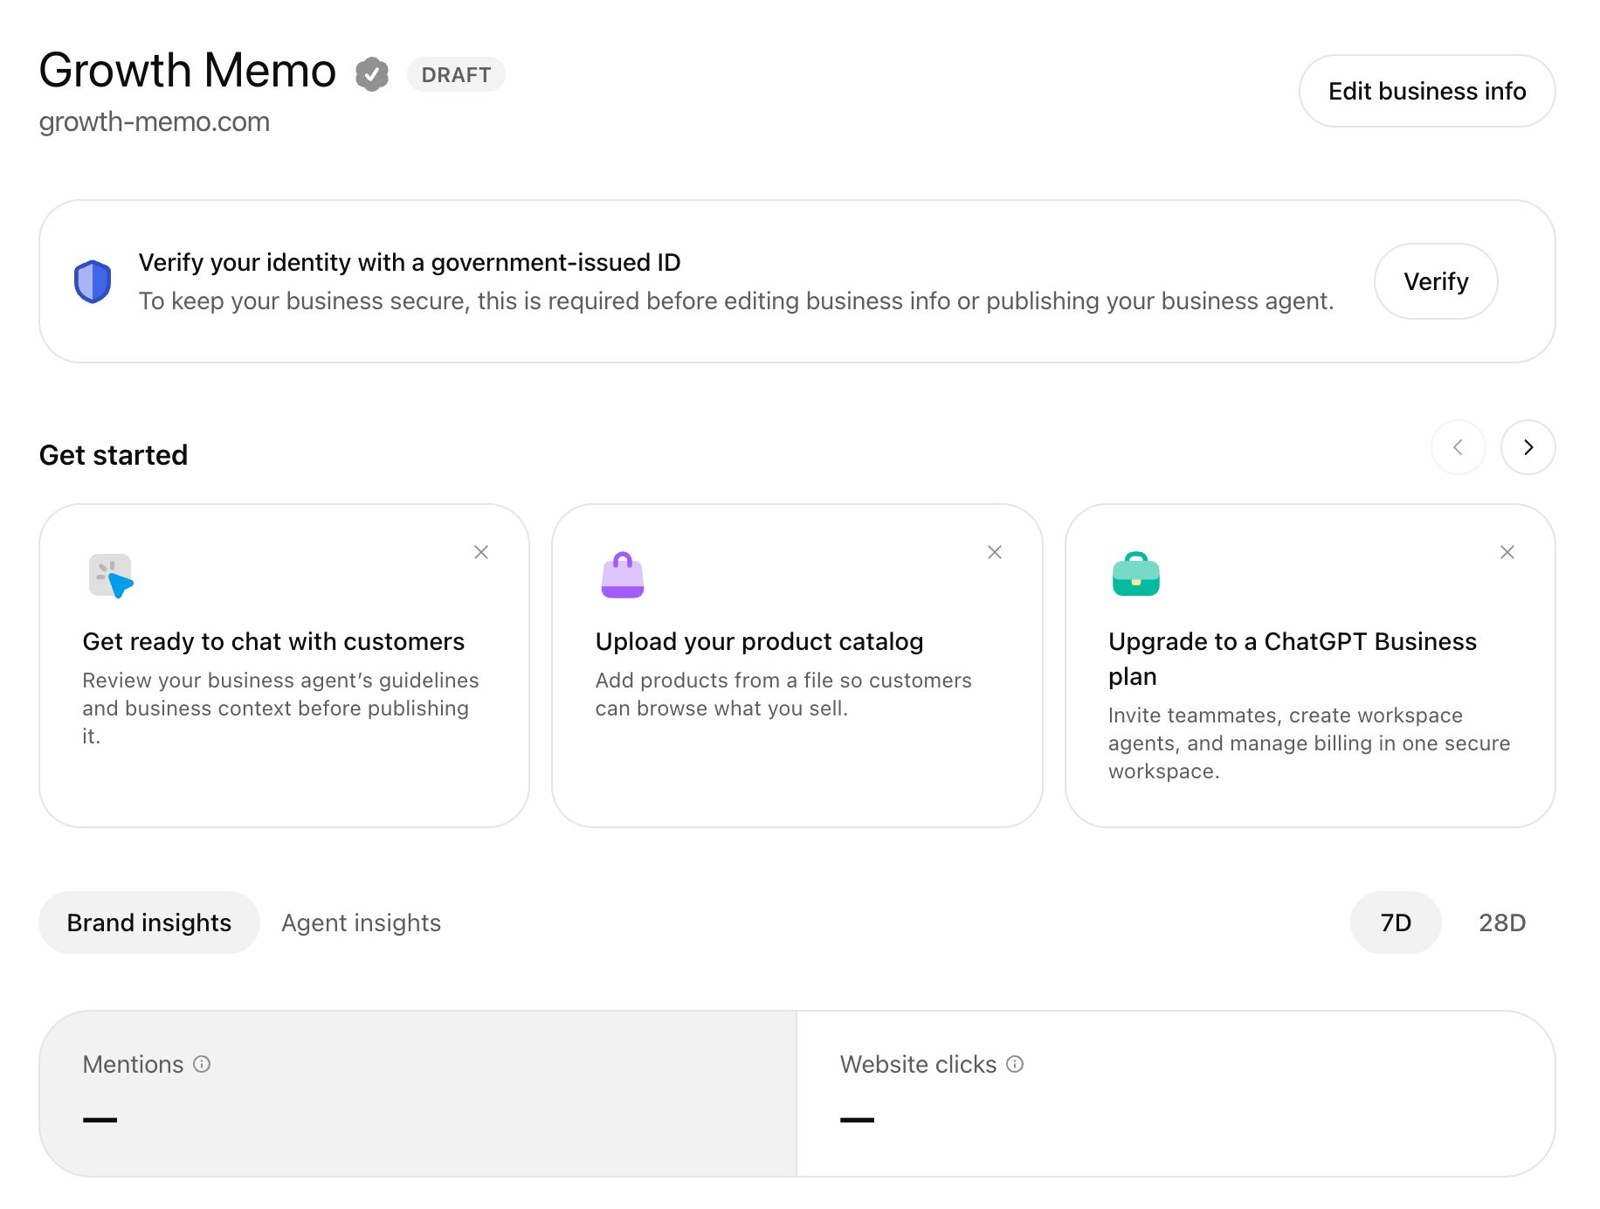 409 interactions · 2d agoTrending topicBraze+351% vs prior 30d · 0.5% of the conversationTrending topicHeyReach+111% vs prior 30d · 0.9% of the conversationTrending topicRB2B+90.6% vs prior 30d · 0.7% of the conversationTrending topicForward Deployed Engineering+83.0% vs prior 30d · 1.0% of the conversationTrending topicEntrepreneurship+55.6% vs prior 30d · 1.3% of the conversation
 Braze↑63 places in GTM Developer Tools
 Base44↑5 places in Coding Agents & Harnesses for GTM
 Ploy↑23 places in AI-Native GTM Challengers
 TitanX↑22 places in AI-Native GTM Challengers
 Polytomic↑35 places in GTM Developer Tools
Trending Topics
Brand+351%vs prior 30d0.5%shareMarket Moves
 Post ↗
 111 engagements · 0.6× usualPost ↗
 85 engagements · 1.0× usualPost ↗
 629 engagements · 3.9× usualPost ↗2,091 engagements · 22.6× usualPost ↗
 1 engagementsPost ↗970 engagements · 1.0× usualPost ↗
GTM Tech Index
Latest Posts
Nov 12Paid media agents are comingThe vendors and builders. Why paid is first. My experiments. The autonomy question. Nov 5Everything I measured in AI x GTM -- October reportBuild vs. buy, marketing agents are coming, the new inbound, and categories blurring.
 Oct 29We're going to build it ourselvesThe new stack, two paths for GTM, agents vs infra
Tracking key moves in GTM tech since June 2026. See methodology. Something missing? Send it to adam[at]adamgtm.com
All topics
BetaFigures move as the panel grows and definitions sharpen.
+27.4%vs prior 30d+7.5%vs prior 30d-14.9%vs prior 30d+0.1%vs prior 30d+38.2%vs prior 30d-31.5%vs prior 30d+5.4%vs prior 30d -43.1%vs prior 30d+20.6%vs prior 30d
 +30.7%vs prior 30d
 +110%vs prior 30d-20.4%vs prior 30d+11.2%vs prior 30d+111%vs prior 30d-21.7%vs prior 30d-15.8%vs prior 30d+58.5%vs prior 30d-16.4%vs prior 30d-4.4%vs prior 30d+48.1%vs prior 30d+15.7%vs prior 30d+90.6%vs prior 30d+30.3%vs prior 30d-14.7%vs prior 30d
 +522%vs prior 30d+154%vs prior 30d-62.3%vs prior 30d+15.7%vs prior 30d+15.5%vs prior 30d+0.8%vs prior 30d+18.5%vs prior 30d+351%vs prior 30d-28.3%vs prior 30d+0.2%vs prior 30d+3.0%vs prior 30d+2.1%vs prior 30d-34.1%vs prior 30d-33.1%vs prior 30dNEWvs prior 30d
 +35.3%vs prior 30d
 -37.4%vs prior 30d
 -16.5%vs prior 30d+147%vs prior 30d
 -27.4%vs prior 30d-41.4%vs prior 30d+11.3%vs prior 30d
 +9.0%vs prior 30d
 +4.3%vs prior 30d
 +2.8%vs prior 30d
 -14.3%vs prior 30d
 +76.3%vs prior 30d
 -49.2%vs prior 30d
 +3.3%vs prior 30d-53.0%vs prior 30d
 -25.9%vs prior 30d
 +45.6%vs prior 30d
 -77.3%vs prior 30d
 ±0%vs prior 30d
 -68.7%vs prior 30d-31.9%vs prior 30d
 -40.7%vs prior 30d
 -47.7%vs prior 30d
 -58.8%vs prior 30d-71.3%vs prior 30d
 +34.2%vs prior 30d+43.8%vs prior 30d
Nothing matches this filter.
The tools and practices teams use to build agents for sales, marketing and RevOps.
GTM agent building lost conversation share from April through October, with a brief August pause; the last 30 days are down another 11.4%. No single event explains the slide: the posts span Cody Schneider’s setup guide, ColdIQ’s reusable ad skills and Greg Isenberg’s connected agent workflows. Practical examples persist even as the topic takes a smaller share of attention.
Posts to understand this
Inside Building GTM Agents
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Grok Bot | 76 |
| 3 | Codex | 82 |
| 4 | Clay | 93 |
| 5 | Cursor (Anysphere) | 75 |
| 6 | HubSpot | 89 |
| 7 | Salesforce | 94 |
| 8 | Lovable | 60 |
| 9 | Instantly | 66 |
| 10 | Replit | 55 |
How brands earn visibility, citations and recommendations inside AI answers.
AEO/GEO rose into June, eased through September, then recovered in October; the last 30 days are up 24.2%. The evidence traces a shift from investment and product promotion, including Daydream’s $15 million round and HubSpot’s Loverboy campaign, to broader adoption: Kyle Poyar’s October report names AEO as the channel with the biggest adoption increase.
Posts to understand this · as of Nov 4
Inside AEO/GEO
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 52 |
| 2 | HubSpot | 89 |
| 3 | Ahrefs | 50 |
| 4 | Clay | 93 |
| 5 | Semrush | 46 |
| 6 | Claude Code | 99 |
| 7 | AirOps | 41 |
| 8 | Salesforce | 94 |
| 9 | Grok Bot | 76 |
| 10 | G2 | 58 |
Marketing that delivers value in the feed or answer instead of forcing a click or form fill.
Zero-click marketing peaked in May, declined through September and rebounded in October; the last 30 days are nearly flat, down 1.8%. The posts trace a debate that has become more qualified: Dave Gerhardt challenges download-based funnels, Wil Reynolds emphasizes accumulated brand authority, and Amanda Natividad cites evidence that links can still work. October’s renewed discussion includes scrutiny of zero-click rules themselves.
Posts to understand this
Inside Zero-Click Marketing Strategies
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Clay | 93 |
| 3 | Profound | 52 |
| 4 | Ahrefs | 50 |
| 5 | Semrush | 46 |
| 6 | Claude Code | 99 |
| 7 | AirOps | 41 |
| 8 | Salesforce | 94 |
| 9 | Grok Bot | 76 |
| 10 | Instantly | 66 |
The people, tools and operating model behind custom go-to-market systems.
GTM Engineering eased from its May high through September, then held near 7% in October; the last 30 days are up just 1.8%. Clay’s $115 million raise and October global agent launch gave the conversation concrete product news, while reports of in-house hiring kept the career story alive. Together, they fit a plateau around implementation and roles.
Posts to understand this · as of Nov 5
Inside GTM Engineering
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 89 |
| 4 | Instantly | 66 |
| 5 | Salesforce | 94 |
| 6 | Prospeo | 54 |
| 7 | HeyReach | 55 |
| 8 | Codex | 82 |
| 9 | Grok Bot | 76 |
| 10 | AI Ark | 48 |
How software exposes its data and actions so agents can use it directly.
Conversation share peaked in May, declined through August, briefly recovered in September, then fell to 6.03% in October; the overlapping last 30 days show a 17.4% decline. The selected posts focus on the plumbing for agent access: Cloudflare’s planned paid gateway, Notion’s developer tools, and Databox’s connector giving Claude access to business metrics.
Posts to understand this · as of Nov 9
Inside Headless & Agent Interfaces
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 94 |
| 3 | HubSpot | 89 |
| 4 | Clay | 93 |
| 5 | Grok Bot | 76 |
| 6 | Instantly | 66 |
| 7 | Codex | 82 |
| 8 | Cursor (Anysphere) | 75 |
| 9 | Exa.ai | 51 |
| 10 | HeyReach | 55 |
The choice between open models and closed APIs, including cost, control, quality and lock-in.
Open vs. Closed Models climbed to a July high, when Hugging Face amplified NVIDIA's support for open models, then declined through October. October announcements from Mistral and Kimi supplied fresh capability claims, but did not restore the summer's share. The last 30 days are up 5.3%, a modest pickup within a broader 90-day decline.
Posts to understand this · as of Nov 8
Inside Open vs. Closed Models
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Cursor (Anysphere) | 75 |
| 3 | Codex | 82 |
| 4 | OpenRouter | 53 |
| 5 | Replit | 55 |
| 6 | Salesforce | 94 |
| 7 | Canva | 51 |
| 8 | Grok Bot | 76 |
| 9 | Baseten | 43 |
| 10 |  Together AI | 33 |
How teams use buyer signals to decide who to target, when and why.
Signal-Based Sales & ABM lost share from May through August, recovered through October and is now nearly flat, up 1.9% over the last 30 days. No single event explains that path. The recurring thread is practical execution: shared-context outbound agents, repeatable plays with Clay and Claude Code, and solutions by stc's use of intent data across key accounts.
Posts to understand this
Inside Signal-Based Sales & ABM
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | HubSpot | 89 |
| 3 | Claude Code | 99 |
| 4 | Salesforce | 94 |
| 5 | Instantly | 66 |
| 6 | HeyReach | 55 |
| 7 | AI Ark | 48 |
| 8 | RB2B | 50 |
| 9 | 6sense | 46 |
| 10 | Grok Bot | 76 |
How companies prove AI delivers enough value to move beyond a pilot.
Conversation share held near 7–8% from April through July, then declined each month through October. The last 30 days show a further 15.3% drop despite continued posts about controlling model costs, prioritizing valuable deployments, and proving that AI spending delivers value beyond experimental budgets.
Posts to understand this
Inside Proving AI ROI
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | Clay | 93 |
| 4 | Grok Bot | 76 |
| 5 | Codex | 82 |
| 6 | Cursor (Anysphere) | 75 |
| 7 | HubSpot | 89 |
| 8 | Replit | 55 |
| 9 | Canva | 51 |
| 10 | Intercom | 43 |
How teams create, distribute and judge marketing content made with AI.
AI Content stayed near 4–5% through August before losing share in September and October; the last 30 days are down 9.4%. The posts offer a steady sequence of workflow improvements, rather than one event that explains the decline: Runway added delivery formats, Higgsfield expanded access inside creative tools and ChatGPT, and fal launched faster, discounted video generation.
Posts to understand this
Inside AI Content
| Brand | GTM Index | |
|---|---|---|
| 1 | Higgsfield | 41 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 89 |
| 4 | Clay | 93 |
| 5 |  HeyGen | 33 |
| 6 | Runway | 36 |
| 7 | ElevenLabs | 56 |
| 8 | Canva | 51 |
| 9 | Replit | 55 |
| 10 | Apify | 54 |
How large companies move AI from small pilots into secure, useful production work.
Enterprise AI adoption’s share nearly halved between April and October, and the last 30 days are down 18%. The posts frame a recurring gap between ambition and execution: Steve Nouri questions pilot value, while Lindsay Rothlisberger describes undocumented processes that delay builds. Vanta’s reported $300 million ARR milestone offers a concrete success story within that broader friction.
Posts to understand this
Inside Enterprise AI Adoption
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 94 |
| 3 | Clay | 93 |
| 4 | Codex | 82 |
| 5 | Grok Bot | 76 |
| 6 | Cursor (Anysphere) | 75 |
| 7 | HubSpot | 89 |
| 8 | Nooks | 48 |
| 9 | Zapier | 52 |
| 10 |  Monaco | 30 |
Agents that do go-to-market work across marketing and sales, rather than the tools people use to build them.
Agents for GTM fell sharply from April through July, then recovered gradually through October; the last 30 days are up 14.6%. Fin’s April sales role and Clay’s October campaign agent frame a recurring pattern of agents taking on specific revenue work. Nooks’ November funding and deal-agent announcements add fresh evidence of that expansion.
Posts to understand this · as of Nov 5
Inside Agents for GTM
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Salesforce | 94 |
| 3 | Claude Code | 99 |
| 4 | HubSpot | 89 |
| 5 | Nooks | 48 |
| 6 | Vercel | 60 |
| 7 | Grok Bot | 76 |
| 8 | Exa.ai | 51 |
| 9 | ZoomInfo | 52 |
| 10 | Codex | 82 |
How AI changes what software companies build, charge for and deliver.
After a May high and a summer decline, the conversation settled near 2.9% share in September and October; the last 30 days are up just 2.1%. The plateau holds competing evidence: ElevenLabs cut prices, Salesforce reported seat growth and low attrition, and Adam argued vendors must sell agents or their infrastructure. The business model debate persists without a single verdict.
Posts to understand this · as of Nov 3
Inside Software Business Model Disruption
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 93 |
| 3 | HubSpot | 89 |
| 4 | Claude Code | 99 |
| 5 | Vercel | 60 |
| 6 | Exa.ai | 51 |
| 7 | Gong | 62 |
| 8 | Cursor (Anysphere) | 75 |
| 9 | ZoomInfo | 52 |
| 10 | Codex | 82 |
How companies keep agents secure, accountable and under control as they take on real work.
Agent Governance climbed from April to July, then declined each full month through October; share is down 25% over the last 30 days. The posts do not identify a trigger for either turn. They show a persistent evaluation problem across coding rules, Anthropic's report of benchmark answer discovery and September guidance on tasks and verifiers, despite the smaller conversation share.
Posts to understand this
Inside Agent Governance
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 94 |
| 3 | Clay | 93 |
| 4 | Codex | 82 |
| 5 | HubSpot | 89 |
| 6 | OpenRouter | 53 |
| 7 | Vercel | 60 |
| 8 | Cursor (Anysphere) | 75 |
| 9 | Grok Bot | 76 |
| 10 | Canva | 51 |
How companies build trust and stand out when AI makes content cheap and abundant.
August’s rebound gave way to two months of lower conversation share, with another 7.6% decline over the last 30 days. The recurring thread is human accountability as AI content spreads: Ann Handley challenged authenticity policing, Clay published an AI writing policy, and Zappi tested how surprise helps ads stand out without losing brand recognition.
Posts to understand this
Inside Brand & Authenticity
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 89 |
| 4 | Salesforce | 94 |
| 5 | Grok Bot | 76 |
| 6 | Vercel | 60 |
| 7 | Cursor (Anysphere) | 75 |
| 8 | Lovable | 60 |
| 9 |  Primer | 32 |
| 10 | Apify | 54 |
How AI changes software pricing, usage costs and gross margins.
After a June high of 4.7%, conversation share fell to 2.0% in October; the last 30 days are essentially flat at +0.4%. The posts trace a shift from OpenAI’s token price cuts to Rippling’s spend controls and Peter Walker’s cache economics. That pattern gives the plateau substance: attention persists around managing actual bills.
Posts to understand this · as of Nov 9
Inside AI Pricing & Margins
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | Clay | 93 |
| 4 | HubSpot | 89 |
| 5 | Cursor (Anysphere) | 75 |
| 6 | ZoomInfo | 52 |
| 7 | Gong | 62 |
| 8 | OpenRouter | 53 |
| 9 | Exa.ai | 51 |
| 10 | Codex | 82 |
Agents that do sales work, from prospecting and outbound to the AI SDR.
April’s high coincided with Fin launching a sales role and HockeyStack announcing $50 million for revenue agents. Share declined through August before modest gains in September and October; the last 30 days are up 8.9%. Jeff Ignacio’s early-November post illustrates a narrower use-case argument around research, simple outreach, and inbound intake, rather than another broad launch promise.
Posts to understand this · as of Nov 5
Inside Agents for Sales
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Salesforce | 94 |
| 3 | Claude Code | 99 |
| 4 | HubSpot | 89 |
| 5 | Nooks | 48 |
| 6 | Vercel | 60 |
| 7 | Exa.ai | 51 |
| 8 | Grok Bot | 76 |
| 9 | Monaco | 30 |
| 10 |  Sumble | 35 |
Marketing built on real people, earned trust and experiences AI cannot easily copy.
After holding around 2.4–2.5% through summer, conversation share dropped in September and recovered modestly in October; the last 30 days are flat at -0.5%. No single event explains the curve. The recurring thread is credibility through people: Wispr Flow’s founder content and Chris Donnelly’s personal-brand account sit alongside skepticism about AI-mediated authenticity.
Posts to understand this · as of Nov 9
Inside Human Experience
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | HubSpot | 89 |
| 3 | Claude Code | 99 |
| 4 | Salesforce | 94 |
| 5 | Nooks | 48 |
| 6 | Grok Bot | 76 |
| 7 | Lovable | 60 |
| 8 | Vercel | 60 |
| 9 | Apify | 54 |
| 10 | Instantly | 66 |
Software that performs SDR work, and how it changes the human SDR role.
AI SDR fell by more than half, from 3.4% in April to 1.48% in July, then settled between 1.6% and 1.9%. Ava 2.0 opened the period promising full autonomy. By September, Yuriy Zaremba's Ami launch was saying the market overpromised. The last 30 days are flat, up 1.2%, so the category is holding at a lower level.
Posts to understand this · as of Nov 4
Inside AI SDR
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Salesforce | 94 |
| 3 | Claude Code | 99 |
| 4 | HubSpot | 89 |
| 5 | Vercel | 60 |
| 6 | Exa.ai | 51 |
| 7 | Grok Bot | 76 |
| 8 | Instantly | 66 |
| 9 | Monaco | 30 |
| 10 | Primer | 32 |
How revenue teams give agents the knowledge, memory and context they need to work.
Context engineering rose through June, then lost share every completed month through October; the last 30 days are down 27.9%. The posts trace a shift from context as a standalone discipline to context inside working systems: Charlie Hills describes harness engineering, Stevie Case documents Ask Ilma’s reliance on help articles, and Seth London outlines agents that act on warehouse signals.
Posts to understand this · as of Nov 4
Inside Context Engineering in GTM
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Claude Code | 99 |
| 3 | Grok Bot | 76 |
| 4 | Salesforce | 94 |
| 5 | HubSpot | 89 |
| 6 | Codex | 82 |
| 7 | ZoomInfo | 52 |
| 8 | Rox | 32 |
| 9 |  Clearskies | 21 |
| 10 | Exa.ai | 51 |
How people and agents share work, hand off tasks and make decisions together.
Multi-player AI held a fairly steady share from June through September after its May high, then dropped in October; the last 30 days are down 33.1%. Dust’s shared-context pitch, Grok Bot’s early beta and September’s team bots show repeated attempts to establish AI teammates. Those announcements supplied continuity, but did not sustain the earlier level of conversation.
Posts to understand this
Inside Multi-Player AI
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 89 |
| 3 | Clay | 93 |
| 4 | Claude Code | 99 |
| 5 |  Viktor | 36 |
| 6 | Vercel | 60 |
| 7 | Instantly | 66 |
| 8 | Gong | 62 |
| 9 | HeyReach | 55 |
| 10 | Nooks | 48 |
Growth driven by people using the product before they talk to sales.
Product-led growth declined through July, recovered some share in August, then softened through October; the last 30 days are down 6.6%. No single event explains that path, but the posts share a practical theme: Clay combines product-led and sales-led growth, Metronome opens self-service access, and 1up argues for faster buyer access to answers and demos.
Posts to understand this · as of Nov 4
Inside Product-Led Growth
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | HubSpot | 89 |
| 3 | Salesforce | 94 |
| 4 | Claude Code | 99 |
| 5 | Primer | 32 |
| 6 | Ahrefs | 50 |
| 7 | Gong | 62 |
| 8 | Ploy | 31 |
| 9 | ZoomInfo | 52 |
| 10 | Codex | 82 |
Low-quality AI content and the fight to make automated work worth reading.
AI Slop held near 2% from April through June, then softened unevenly through October; no single event in the posts explains the decline. The recurring complaint shifts from empty content at scale to authenticity policing and repetitive AI comments. The latest 30 days are nearly flat at +1.7%, so November’s first eight days do not establish a rebound.
Posts to understand this · as of Nov 8
 inContent critiqueMarketing diary skewers a CEO’s push to replace content strategy with ClaudeAH
 inAuthenticity backlashAnn Handley criticizes AI detection pressures and tools that disguise generated writingPW
 inComment fatiguePeter Walker calls out repetitive AI comments across several of his posts
Inside AI Slop
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Grok Bot | 76 |
| 3 | HubSpot | 89 |
| 4 | Substack | 52 |
| 5 | Apify | 54 |
| 6 | Clay | 93 |
| 7 | Exa.ai | 51 |
| 8 | Gamma | 45 |
| 9 | HeyGen | 33 |
| 10 | Instantly | 66 |
Agents that do marketing work, from campaigns and content to paid media and answering inbound demand.
Share slid from 1.6% in April to 0.6% in July, with a flat May and June when Kieran Flanagan sketched an agentic marketing org. It rebounded to 0.9% in August, before either Clay post, and held through the September Series D. Clay's Sculpt launch lined up with October's rise to 1.2%, and share is up 39% over the last 30 days.
Posts to understand this · as of Nov 4
Inside Agents for Marketing
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 89 |
| 4 | Salesforce | 94 |
| 5 | Vercel | 60 |
| 6 | ZoomInfo | 52 |
| 7 | Apify | 54 |
| 8 | Braze | 39 |
| 9 |  Docket | 33 |
| 10 | Exa.ai | 51 |
How teams track and control the cost of models, tokens and agent work.
Token costs rose in share through July, when OpenAI announced steep Luna and Terra price cuts, then declined through October; the last 30 days are down 40.5%. Later posts shift from cheaper tokens to exposure: Harvey’s reported margin squeeze and Mutiny’s lost six-figure deal. Those examples keep cost control concrete without explaining the broader decline.
Posts to understand this · as of Nov 7
Inside Token Spend & Cost Controls
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 94 |
| 3 | Canva | 51 |
| 4 | OpenRouter | 53 |
| 5 | Clay | 93 |
| 6 | Cursor (Anysphere) | 75 |
| 7 | Higgsfield | 41 |
| 8 | Grok Bot | 76 |
| 9 | Intercom | 43 |
| 10 | Replit | 55 |
AI agents that run errands, email and purchases for one person, and the race to become the one people trust with their accounts.
Personal agents moved from a quiet spring and summer to a sharp September and October expansion. Sierra and Meta’s October Personal Agent Protocol announcement supplied a concrete business-facing development, with Shopify, Stripe and Walmart among the partners; it does not explain September’s initial jump. The last 30 days are down 21.8%, so attention is cooling after that expansion.
Posts to understand this · as of Nov 8
Inside Personal Agents
| Brand | GTM Index | |
|---|---|---|
| 1 | Grok Bot | 76 |
| 2 | Claude Code | 99 |
| 3 | Codex | 82 |
| 4 | HubSpot | 89 |
| 5 | Salesforce | 94 |
| 6 | Replit | 55 |
| 7 |  Cline | 31 |
| 8 | Cursor (Anysphere) | 75 |
| 9 | Granola | 53 |
| 10 | Lovable | 60 |
The argument that agents and custom software will break the classic SaaS model.
SaaSpocalypse’s share fell from 2.5% in April to below 1% in October, with little movement in August and September; the last 30 days are down 21.5%. The posts repeatedly qualify the death claim: Intercom backs both Fin and its help desk, Salesforce reports seat growth, and Cargo argues agents become software’s primary users. The debate increasingly concerns software’s customers and design.
Posts to understand this
Inside SaaSpocalypse
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Salesforce | 94 |
| 3 | HubSpot | 89 |
| 4 | Claude Code | 99 |
| 5 | Vercel | 60 |
| 6 | Apify | 54 |
| 7 | Exa.ai | 51 |
| 8 | Gong | 62 |
| 9 | ZoomInfo | 52 |
| 10 | Cursor (Anysphere) | 75 |
The choice between building software internally and buying another product.
Build vs. Buy declined from April through July, steadied in August and September, then fell again in October; the last 30 days are down 30.4%. The posts move from broad SaaS replacement arguments to specific choices: a salesperson’s Replit tools and a broken Reflector app with limited support. That pattern grounds the debate without identifying a single cause for its decline.
Posts to understand this
Inside Build vs. Buy
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | HubSpot | 89 |
| 3 | Salesforce | 94 |
| 4 | Vercel | 60 |
| 5 | Apify | 54 |
| 6 | Exa.ai | 51 |
| 7 | Claude Code | 99 |
| 8 | OpenRouter | 53 |
| 9 | ZoomInfo | 52 |
| 10 | Cursor (Anysphere) | 75 |
Ways to verify whether digital content or online activity came from a person or AI.
Proof of Human’s August spike aligns with Anthropic’s watermarking FAQ and debate over whether AI-content users should welcome disclosure. Share fell back in September and stayed nearly level in October, when Evan Armstrong posted a Pangram-based check of Anthropic’s content. The last 30 days are down 12.5%, consistent with an announcement-led burst followed by occasional scrutiny.
Posts to understand this · as of Nov 8
Inside Proof of Human
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HeyGen | 33 |
| 3 | Instantly | 66 |
| 4 | Substack | 52 |
| 5 | Apify | 54 |
| 6 | Exa.ai | 51 |
| 7 | Grok Bot | 76 |
| 8 |  People Data Labs | 24 |
| 9 | Replit | 55 |
| 10 |  AppsFlyer | 19 |
AI tools that write, edit, test and operate software alongside a human builder.
Coding agents’ share declined from 20.3% in April to 11.6% in October, with only a brief August lift; the last 30 days are down 7.7%. Vercel’s performance rules and Notion’s workspace-as-code beta show practical development uses, while Cursor’s October notice adds a security incident. The evidence spans tooling and operational risk, rather than one event that explains the sustained decline.
Posts to understand this · as of Nov 7
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Grok Bot | 76 |
| 3 | Codex | 82 |
| 4 | Cursor (Anysphere) | 75 |
| 5 | Clay | 93 |
| 6 | HubSpot | 89 |
| 7 | Lovable | 60 |
| 8 | Salesforce | 94 |
| 9 | Replit | 55 |
| 10 | Instantly | 66 |
The practice of helping a brand appear, earn citations and get recommended inside AI answers.
AEO eased from its May high through September, then rebounded in October; the last 30 days are up 13.8%, despite a weaker 90-day trend. The posts frame a persistent measurement debate, from Ahrefs' visibility research to SEO fundamentals. October added a specific concern: Ethan Smith attributed a roughly 45% drop in tracked ChatGPT sessions to missing referral signals.
Posts to understand this · as of Nov 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 52 |
| 2 | HubSpot | 89 |
| 3 | Ahrefs | 50 |
| 4 | Semrush | 46 |
| 5 | Clay | 93 |
| 6 | AirOps | 41 |
| 7 | Claude Code | 99 |
| 8 | Salesforce | 94 |
| 9 | Grok Bot | 76 |
| 10 | Webflow | 48 |
The frontier models and labs that provide the base layer for AI products.
Foundation Models swung between July and September highs and sharp pullbacks, with share now down 7.8% over the last 30 days. The posts show recurring releases and comparisons, rather than one event that explains those swings: Anthropic introduced Glasswing, Arena compared agent delivery and user experience, and Claude announced Fable 5.2 and Mythos 5.2 in early November.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 82 |
| 3 | Cursor (Anysphere) | 75 |
| 4 | Grok Bot | 76 |
| 5 | HubSpot | 89 |
| 6 | Granola | 53 |
| 7 | Midjourney | 33 |
| 8 | Salesforce | 94 |
| 9 | OpenRouter | 53 |
| 10 | ElevenLabs | 56 |
An open protocol that lets agents connect to a product's data, tools and actions.
MCP's share declined from 7.7% in May to 4.3% in October, and the last 30 days are down another 26.3%. Product integrations continued throughout that slide: ElevenLabs added agent management in Claude, Databox connected business context to analysis and actions, and Monarch restored MCP access across plans. The pattern is continued product adoption alongside less conversation share.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 89 |
| 3 | Salesforce | 94 |
| 4 | Clay | 93 |
| 5 | Instantly | 66 |
| 6 | Cursor (Anysphere) | 75 |
| 7 | Codex | 82 |
| 8 | Gong | 62 |
| 9 | HeyReach | 55 |
| 10 | Exa.ai | 51 |
Buying attention through paid search, paid social, display and other advertising channels.
Paid Media rose gradually through summer, dipped in September, then jumped to 3.4% in October; share is up 34.3% over the last 30 days. The evidence spans Clay Ads' August launch, Anthropic's October growth marketing hire and reusable Claude skills for ad operations in early November. Together, they show sustained attention to audience targeting, performance measurement and routine campaign work.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Claude Code | 99 |
| 3 | Clay | 93 |
| 4 | Salesforce | 94 |
| 5 | Instantly | 66 |
| 6 | Primer | 32 |
| 7 | Grok Bot | 76 |
| 8 | Codex | 82 |
| 9 | RB2B | 50 |
| 10 | Apify | 54 |
Measuring whether AI answers mention, cite and recommend a brand.
AI Visibility reached 4% in June, slipped through September and recovered in October; the last 30 days are up 20%. The conversation includes a dispute over what visibility is worth: Steve Toth argues for active optimization, while Rand Fishkin's October critique questions business impact outside Google's AI surfaces. Checkthat's earlier launch adds another distinction: tracking mentions does not itself improve them.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Profound | 52 |
| 2 | AirOps | 41 |
| 3 | Ahrefs | 50 |
| 4 | G2 | 58 |
| 5 | Semrush | 46 |
| 6 | Clay | 93 |
| 7 | HubSpot | 89 |
| 8 |  SparkToro | 29 |
| 9 | Vercel | 60 |
| 10 | Claude Code | 99 |
Email sent to people with no prior relationship to start a sales conversation.
Cold email spiked in May, faded through October and is now up 16.5% over the last 30 days. Jason Bay’s reported reply lift from manual inbox sends gives May a concrete deliverability story; later posts debate broad outreach and durable infrastructure. The recurring question is whether the sending setup can support the volume, with no single event explaining the recent lift.
Posts to understand this
 inInbox experimentJason Bay reports replies rose after switching from sequencer to inboxS
 inInfrastructure guidanceSmartlead interviews Zapmail’s CEO about mailbox limits and infrastructure durabilityMS
 XVolume argumentMichael Saruggia advocates repeated market outreach with frequent infrastructure changes
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Claude Code | 99 |
| 3 | Instantly | 66 |
| 4 | HubSpot | 89 |
| 5 | Salesforce | 94 |
| 6 | HeyReach | 55 |
| 7 | Prospeo | 54 |
| 8 | n8n | 58 |
| 9 | AI Ark | 48 |
| 10 | Grok Bot | 76 |
Finding, researching and qualifying the people and accounts a sales team should contact.
Spring was the high, with launches like Origami, the YC-backed AI that finds customers automatically. Share sank to 2.3% by September. October's rebound came with Adam Robinson's Moltsets launch, an unlimited contact database at $27 a month aimed at ZoomInfo and Apollo, and the line is up 26.9% over 30 days, though down 14.5% over 90.
Posts to understand this · as of Nov 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 89 |
| 4 | Instantly | 66 |
| 5 | Salesforce | 94 |
| 6 | AI Ark | 48 |
| 7 | Prospeo | 54 |
| 8 | HeyReach | 55 |
| 9 | n8n | 58 |
| 10 | Findymail | 45 |
The team that runs go-to-market systems, processes, data and reporting across revenue functions.
RevOps lost share from April through August, then held near 2.8% through October; the last 30 days remain slightly down at 2.9%. The posts show a practical debate rather than one defining event: which weekly tasks deserve agents, how Claude can help model Salesforce pipeline, and why rebuilding cheap SaaS can waste the team's time.
Posts to understand this · as of Nov 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 93 |
| 3 | HubSpot | 89 |
| 4 | Claude Code | 99 |
| 5 | Instantly | 66 |
| 6 | Gong | 62 |
| 7 | HeyReach | 55 |
| 8 | n8n | 58 |
| 9 | Nooks | 48 |
| 10 | ZoomInfo | 52 |
The work of retaining customers, helping them succeed and expanding the relationship.
Customer success lost share from April through July, rebounded in August, then slipped in September; the last 30 days are up 14.4%. The posts share a revenue focus rather than a single catalyst: Rox pitches automated renewals, Vanta unifies new sales and expansion, and Higgsfield describes a $99 subscriber's company reaching a $6 million annual contract.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 93 |
| 3 | HubSpot | 89 |
| 4 | Claude Code | 99 |
| 5 | Gong | 62 |
| 6 | G2 | 58 |
| 7 | Vercel | 60 |
| 8 | Exa.ai | 51 |
| 9 | Nooks | 48 |
| 10 | Cursor (Anysphere) | 75 |
How large organizations adopt AI, move beyond pilots and change how work gets done.
Enterprise AI’s conversation share declined every month from April through October and is down another 21.4% over the last 30 days. No single event explains the slide; the posts consistently address deployment friction, from Mistral’s Workflows preview to Informatica’s trusted data argument and Dust’s partnership with Artefact, which established governance at Bpifrance across a 500-license deployment.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | Clay | 93 |
| 4 | Codex | 82 |
| 5 | Grok Bot | 76 |
| 6 | Cursor (Anysphere) | 75 |
| 7 | HubSpot | 89 |
| 8 | Monaco | 30 |
| 9 | Rox | 32 |
| 10 | Zapier | 52 |
Voice and chat software that talks with buyers and customers.
Conversational AI’s share rose from April through August, flattened in September, then climbed in October; the latest 30 days are up 14.1%. A cluster of voice launches arrived in late October: Mistral’s speech models and agent SDK, ElevenLabs’ speech-to-speech models, and Cartesia’s managed enterprise agents.
Posts to understand this · as of Nov 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | G2 | 58 |
| 3 | Grok Bot | 76 |
| 4 | ElevenLabs | 56 |
| 5 | HubSpot | 89 |
| 6 | Docket | 33 |
| 7 | Clay | 93 |
| 8 |  Vector | 34 |
| 9 |  11x | 24 |
| 10 | Attio | 51 |
Marketing programs that create and capture demand, then turn it into pipeline.
Demand generation declined from April into a September–October plateau, with an August bump that coincided with Kyle Coleman taking broader revenue ownership at ClickUp. The last 30 days are up 9.9%, with Webflow Campaigns adding a concrete product launch. Across the posts, attention shifts from lead capture toward revenue accountability and faster campaign execution.
Posts to understand this · as of Nov 5
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Claude Code | 99 |
| 3 | Clay | 93 |
| 4 | Salesforce | 94 |
| 5 | Webflow | 48 |
| 6 |  Optimizely | 33 |
| 7 | Primer | 32 |
| 8 | Docket | 33 |
| 9 | ZoomInfo | 52 |
| 10 | Apify | 54 |
The work of connecting marketing activity to pipeline and revenue.
Attribution returned close to its May high in October after a quieter August and September, with share up 10.7% over the last 30 days. The recurring issue is how to connect exposure to revenue when clicks miss the path: Ethan Smith’s n8n example covers zero-click discovery, while Eli Schwartz’s October Google analysis raises fresh concerns about sharing inside AI search.
Posts to understand this · as of Nov 6
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Clay | 93 |
| 3 | Salesforce | 94 |
| 4 | Gong | 62 |
| 5 | Claude Code | 99 |
| 6 | Docket | 33 |
| 7 | G2 | 58 |
| 8 |  GrowthLoop | 29 |
| 9 | Grok Bot | 76 |
| 10 | HeyReach | 55 |
Cold calls, messages and coordinated outreach used to create new sales opportunities.
Cold Outbound peaked at 3.3% in May, when Nick Palasz's joke about cold-calling brush-offs tapped pain every seller knows. Share then eased to 2.1% by September. The last 30 days are flat at -1.0%, leaving it 19.5% below 90 days ago. Unify's dialer launch adds a product story, but no rebound yet.
Posts to understand this · as of Nov 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 89 |
| 4 | Instantly | 66 |
| 5 | Salesforce | 94 |
| 6 | HeyReach | 55 |
| 7 | Prospeo | 54 |
| 8 | Lemlist | 49 |
| 9 | Nooks | 48 |
| 10 | Apify | 54 |
Adding and verifying contact, company and buying-signal data used by go-to-market teams.
Share peaked at 3.3% in May, then slid to about 1.7% by September. October ticked back up to 1.96%, and the last 30 days are up 11.4%, while the 90-day move is still down 27.8%. In October, Gong launched Gong Enrich with ten data partners, and Christian listed waterfall enrichment in a GTM engineer workflow.
Posts to understand this · as of Nov 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 89 |
| 4 | Instantly | 66 |
| 5 | HeyReach | 55 |
| 6 | Findymail | 45 |
| 7 | Prospeo | 54 |
| 8 | n8n | 58 |
| 9 |  BetterContact | 44 |
| 10 | RB2B | 50 |
People asking AI assistants for answers instead of using a traditional search engine.
AI search lost share after June, stabilized in October, and is up 32.7% over the last 30 days. The recent evidence shifts the question from lost clicks to visibility: Michael King challenges referral-only measurement, while Searchable’s Black Friday research finds citations concentrated on deals, gift, and category pages. That debate gives the renewed attention a concrete commercial focus.
Posts to understand this · as of Nov 7
| Brand | GTM Index | |
|---|---|---|
| 1 | G2 | 58 |
| 2 | Clay | 93 |
| 3 | Salesforce | 94 |
| 4 | Semrush | 46 |
| 5 | Ahrefs | 50 |
| 6 | Profound | 52 |
| 7 | HubSpot | 89 |
| 8 | Primer | 32 |
| 9 | SparkToro | 29 |
| 10 |  CallRail | 25 |
Sales and marketing coordinating around a defined set of target accounts.
ABM’s share held near 2% from April through June, dipped in July, and recovered through October. The last 30 days are down 11.7%, so that recovery has softened. Recent posts focus on coordinating ads, content, and email around target accounts, finding accounts through contact-level intent, and reaching decision-makers before Q1 budgets are set.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | HubSpot | 89 |
| 3 | Salesforce | 94 |
| 4 | Claude Code | 99 |
| 5 | Instantly | 66 |
| 6 | HeyReach | 55 |
| 7 |  Demandbase | 35 |
| 8 | Findymail | 45 |
| 9 | Vector | 34 |
| 10 | 6sense | 46 |
The technical work that keeps outbound email out of spam and inside the inbox.
Deliverability peaked in May, then fluctuated at lower levels through October. Conversation share is up 35.2% over the last 30 days but nearly flat over 90 days, suggesting a rebound rather than sustained growth. October posts highlight the operational work behind email delivery and Resend’s Forge launch, without establishing what caused the recent rise.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | HubSpot | 89 |
| 3 | Claude Code | 99 |
| 4 | Instantly | 66 |
| 5 | n8n | 58 |
| 6 | Prospeo | 54 |
| 7 |  Smartlead | 45 |
| 8 | HeyReach | 55 |
| 9 | Lemlist | 49 |
| 10 | Salesforce | 94 |
Tools and workflows for generating video, avatars and synthetic presenters with AI.
AI Video Generation stepped up in August, held that level in September and eased in October; the posts do not identify the summer catalyst. Higgsfield’s OpenAI Marketplace entry adds a purchasing route, while November’s Lucy 2.6 and Krea Video launches provide early product context. The last 30 days are down 6.7%, despite a 21.3% gain over 90 days.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Higgsfield | 41 |
| 2 | Claude Code | 99 |
| 3 | HeyGen | 33 |
| 4 | Runway | 36 |
| 5 | ElevenLabs | 56 |
| 6 | Canva | 51 |
| 7 | HubSpot | 89 |
| 8 | Replit | 55 |
| 9 | Clay | 93 |
| 10 |  Synthesia | 26 |
Programmable tools used to build custom go-to-market systems, agents and automations.
May’s spike coincided with practical build resources, including Growth Today’s 24 ABM agents, after an April release of 29 Claude skills for cold email. Share faded through August before recovering in September and October, with a 23.6% gain over the last 30 days. The common thread is reusable systems, now illustrated by Jan Rasmussen’s stack for account scoring, signals and outreach.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 89 |
| 4 | Instantly | 66 |
| 5 | Prospeo | 54 |
| 6 | HeyReach | 55 |
| 7 | Findymail | 45 |
| 8 |  FullEnrich | 45 |
| 9 | BetterContact | 44 |
| 10 | AI Ark | 48 |
Mapping and winning the committee of people involved in a business purchase.
Buying Groups eased from May's high, then recovered modestly from August through October; the last 30 days are still down 1.3%. No single event explains the curve: the recurring argument is that deals depend on internal consensus and access across the account, illustrated by Clay's executive outreach and Jon Miller's critique of marketing automation built around MQLs.
Posts to understand this · as of Nov 8
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Clay | 93 |
| 3 | Claude Code | 99 |
| 4 | Salesforce | 94 |
| 5 | Instantly | 66 |
| 6 | HeyReach | 55 |
| 7 | Nooks | 48 |
| 8 | 6sense | 46 |
| 9 | Demandbase | 35 |
| 10 |  Influ2 | 28 |
The warehouses, pipelines and data models that keep customer and revenue data usable.
Conversation share peaked in June, fell each month through October, and is down 12.4% over the last 30 days. The posts do not identify a June catalyst; they trace a recurring need to connect data and execution, from Pocus joining Apollo and Scott Brinker’s Databricks report to Megan Bowen’s October announcement of the Mobi Solutions acquisition and marketing operations services.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 93 |
| 3 | HubSpot | 89 |
| 4 | Claude Code | 99 |
| 5 | Instantly | 66 |
| 6 | GrowthLoop | 29 |
| 7 | Attio | 51 |
| 8 | HeyReach | 55 |
| 9 | Nooks | 48 |
| 10 | Gong | 62 |
How buyers search and how marketers plan, measure and improve organic discovery.
Search Strategy doubled from April to June, then slid to about 1% by September. The last 30 days are up 41%, with October posts going back to practical questions: Austin Armstrong's plan for showing up in Google and ChatGPT, and Kevin Indig's Similarweb data showing AI explains only part of organic search's decline.
Posts to understand this · as of Nov 4
 inPractical planAustin Armstrong lays out a shared SEO and AEO plan built around buyer questions.GN
 inMetric critiqueGaetano Nino DiNardi cites an OtterlyAI test where Google de-indexed slop that LLMs kept citing.KI
 inTraffic dataKevin Indig finds US organic search fell 13.2% over two years, not all from AI.
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Ahrefs | 50 |
| 3 | Semrush | 46 |
| 4 |  Similarweb | 32 |
| 5 | AirOps | 41 |
| 6 | Substack | 52 |
| 7 | Grok Bot | 76 |
| 8 | HubSpot | 89 |
| 9 | Instantly | 66 |
| 10 | Profound | 52 |
The positioning, messaging, launches, competitive work and sales tools owned by product marketing.
April was the high mark at 2.17%, when Profound named a founding marketing engineer and Google's Marvin Chow said he was hiring one too. Share then drifted to about 1.25% by October. The last 30 days are up 6.9%, a small lift off a lower base, with stories like Assent's eight-week repositioning in the mix.
Posts to understand this · as of Nov 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Salesforce | 94 |
| 3 | Claude Code | 99 |
| 4 | HubSpot | 89 |
| 5 | Ploy | 31 |
| 6 | Vercel | 60 |
| 7 | Codex | 82 |
| 8 | Cursor (Anysphere) | 75 |
| 9 | Primer | 32 |
| 10 | Supabase | 50 |
Starting and running a business, including the economics and experience of the founder path.
Entrepreneurship fluctuated around 1% from April through October, but its last 30 days are up 49.9%. The evidence points to a recurring question about founder economics rather than a single catalyst: HubSpot Next launched YouSpot for solo operators, Tally reported $6M ARR with ten people, and Chris Walker challenged the financial rewards of venture funding.
Posts to understand this · as of Nov 8
| Brand | GTM Index | |
|---|---|---|
| 1 | RB2B | 50 |
| 2 | Claude Code | 99 |
| 3 | Clay | 93 |
| 4 | HubSpot | 89 |
| 5 | HeyReach | 55 |
| 6 |  MoltSets | 29 |
| 7 | Instantly | 66 |
| 8 |  Resend | 32 |
| 9 | 6sense | 46 |
| 10 | Codex | 82 |
Tests and benchmarks used to judge whether a model or agent works well enough.
Evals and benchmarks climbed to a July high, settled lower in August and September, then declined in October; the last 30 days are down 43.4%. No supplied event explains the July crest or subsequent retreat. The posts span leaderboard claims, test integrity and Cognition’s October FrontierCode 2.0 launch, which added a concrete debate about engineering judgment without reversing the broader decline.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 94 |
| 3 | Codex | 82 |
| 4 | Grok Bot | 76 |
| 5 | OpenRouter | 53 |
| 6 | Clay | 93 |
| 7 | Cursor (Anysphere) | 75 |
| 8 | ElevenLabs | 56 |
| 9 | Baseten | 43 |
| 10 | Canva | 51 |
The choice of go-to-market motion and the plan for making it work.
GTM Strategy’s share peaked at 2.95% in May, fell to roughly 1.3% by September, and held there in October; the last 30 days are up 1.9%. October and November posts focus on adapting GTM to agent buyers, larger buying committees, and retention when competing products overlap. The discussion centers on who buys, how teams sell, and what keeps customers.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Claude Code | 99 |
| 3 | HubSpot | 89 |
| 4 | Salesforce | 94 |
| 5 | Findymail | 45 |
| 6 | Instantly | 66 |
| 7 | Nooks | 48 |
| 8 | AI Ark | 48 |
| 9 | HeyReach | 55 |
| 10 | Primer | 32 |
Selling large, complex deals through long cycles, procurement, security review and many stakeholders.
Enterprise sales rebounded in August but gave back that gain in September, and the last 30 days are down 16.5% despite October’s small lift. No single deal explains the curve; the recurring debate is what complex selling requires, from Ryan Walsh’s buying-committee checklist to Chris Orlob’s procurement questions and Clay’s account of three sellers who each closed over $1 million.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Cursor (Anysphere) | 75 |
| 2 | Salesforce | 94 |
| 3 | Claude Code | 99 |
| 4 | Clay | 93 |
| 5 | Gong | 62 |
| 6 | Lemlist | 49 |
| 7 | ElevenLabs | 56 |
| 8 | Exa.ai | 51 |
| 9 | Grok Bot | 76 |
| 10 | Instantly | 66 |
The training, fine-tuning and modeling work underneath AI products.
Machine learning rose from June through September before an October pullback; the last 30 days are down 18.5%, despite a 9% gain over 90 days. Skild AI’s S1 launch and World Labs’ announcement that it would join AMD supplied concrete model and hardware stories during the rise. Meta’s October Prometheus report kept training infrastructure in view as share eased.
Posts to understand this · as of Nov 9
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 82 |
| 3 | Cursor (Anysphere) | 75 |
| 4 | HubSpot | 89 |
| 5 | beehiiv | 51 |
| 6 | Together AI | 33 |
| 7 | Baseten | 43 |
| 8 | Midjourney | 33 |
| 9 | Clay | 93 |
| 10 | ElevenLabs | 56 |
Recording and analyzing customer calls to improve coaching, deal execution and revenue decisions.
Conversation intelligence has had an uneven run: a June dip, July rebound, then another slide through September before October recovered. Share is up 35.3% over the last 30 days but down 9.2% over 90 days. Recent posts focus on connecting calls to deal context and updating competitive content, alongside Salesforce’s November 2 announcement of an agreement to acquire Cresta.
Posts to understand this · as of Nov 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Gong | 62 |
| 2 | Salesforce | 94 |
| 3 | HubSpot | 89 |
| 4 | Claude Code | 99 |
| 5 | Clay | 93 |
| 6 | Instantly | 66 |
| 7 | Zapier | 52 |
| 8 | n8n | 58 |
| 9 | HeyReach | 55 |
| 10 | Cursor (Anysphere) | 75 |
How companies create demand, build trust and reach buyers at other businesses.
B2B marketing peaked in June, dropped sharply in July and continued to lose share through October; the last 30 days are down 5.6%. No single announcement explains the decline. Across the posts, the recurring discussion is about where demand comes from: owned audiences, AI search citations, creators and employee voices beyond the founder.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Clay | 93 |
| 3 | Salesforce | 94 |
| 4 | Claude Code | 99 |
| 5 | Optimizely | 33 |
| 6 | Webflow | 48 |
| 7 | Ahrefs | 50 |
| 8 | Primer | 32 |
| 9 | 6sense | 46 |
| 10 |  Conversion | 28 |
B2B brands paying creators and independent voices to reach trusted audiences.
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | HubSpot | 89 |
| 3 | Primer | 32 |
| 4 | beehiiv | 51 |
| 5 | AirOps | 41 |
| 6 | Claude Code | 99 |
| 7 | Apify | 54 |
| 8 | Substack | 52 |
| 9 | Viktor | 36 |
| 10 | ZoomInfo | 52 |
The debate over AI risk, alignment, regulation and responsible development.
AI Safety jumped in September alongside Mercor’s $5 million safety fund and Microsoft’s message about superintelligence serving humanity. October cooled, and the last 30 days are down 38.8%, though share remains above the April-to-August range. ElevenLabs’ Karnataka agreement shows the continuing thread: safety frameworks attached to specific deployments alongside broader research commitments.
Posts to understand this · as of Nov 5
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Grok Bot | 76 |
| 3 | Granola | 53 |
| 4 | Midjourney | 33 |
| 5 | Salesforce | 94 |
| 6 | beehiiv | 51 |
| 7 | Codex | 82 |
| 8 | Cursor (Anysphere) | 75 |
| 9 |  Railway | 34 |
| 10 | Canva | 51 |
Planning, producing and distributing useful content to attract and educate buyers.
Content marketing held near 2% of conversation in May and June, when GrowthX announced GrowthOS, then reached a September low after an uneven summer. The last 30 days are up 9.2%, though the 90-day trend remains down. Recent posts share a clear argument: Sara Stella Lattanzio favors validated ideas over quotas, while Mark Jung connects content to trust before buyers enter the market.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HubSpot | 89 |
| 3 | Grok Bot | 76 |
| 4 | Clay | 93 |
| 5 | HeyReach | 55 |
| 6 | Instantly | 66 |
| 7 | Semrush | 46 |
| 8 | Codex | 82 |
| 9 | G2 | 58 |
| 10 | Nooks | 48 |
Predicting revenue from the pipeline and managing the commitments behind that forecast.
Forecasting reached its high in May, briefly recovered in July, then declined through October; the last 30 days are down 7.6%. No supplied event explains May’s spike. The recurring tension is between autonomous revenue promises from Rox and the work of validating deal signals, visible in Chris Orlob’s contract example and Spotlight.ai’s October pitch.
Posts to understand this · as of Nov 5
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 89 |
| 3 | Clay | 93 |
| 4 | Claude Code | 99 |
| 5 | Gong | 62 |
| 6 |  Clari | 32 |
| 7 | Intercom | 43 |
| 8 | n8n | 58 |
| 9 |  Chili Piper | 37 |
| 10 |  Fireflies | 39 |
How companies sell to other companies and how business buyers make decisions.
B2B sales recovered in October after September’s dip, with conversation share up 7% over the last 30 days but still down over 90 days. The recurring thread is buyer understanding: Maja Voje credits research for outbound results, Morgan Ingram describes renewed interest in personal contact, and Charlotte Lloyd argues that useful questions build trust before a pitch.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | G2 | 58 |
| 2 | Clay | 93 |
| 3 | Claude Code | 99 |
| 4 | HubSpot | 89 |
| 5 | 6sense | 46 |
| 6 | Salesforce | 94 |
| 7 |  Consensus | 26 |
| 8 | Gong | 62 |
| 9 | Grok Bot | 76 |
| 10 | Substack | 52 |
The durable knowledge and memory an agent can use across tasks and sessions.
Agent memory’s share crested in June, then declined through October; the last 30 days are down another 11.8%. The posts trace a practical thread from Claude Code and Obsidian memory to local meeting transcripts and ZoomInfo’s Workbounce acquisition. These are concrete ways to capture reusable context, but they have not sustained the earlier level of conversation.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Claude Code | 99 |
| 3 | Grok Bot | 76 |
| 4 | Salesforce | 94 |
| 5 | Clearskies | 21 |
| 6 | Codex | 82 |
| 7 | Nooks | 48 |
| 8 | ZoomInfo | 52 |
| 9 | Exa.ai | 51 |
| 10 | Gong | 62 |
Engineers embedded with customers to make complex AI products work in the customer's environment.
Forward deployed engineering eased from May through September, then recovered in October; share is up 83.0% over the last 30 days. The evidence points to a practical deployment and hiring story rather than one launch: StackAI describes engineers connecting legacy systems, while Lenny Rachitsky highlights demand for FDE roles. A Palantir alumni critique also questions what qualifies as FDE work.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | ElevenLabs | 56 |
| 4 | Cursor (Anysphere) | 75 |
| 5 | HubSpot | 89 |
| 6 | Lovable | 60 |
| 7 |  PandaDoc | 33 |
| 8 | AirOps | 41 |
| 9 | Clay | 93 |
| 10 | Consensus | 26 |
Scoring leads and accounts to decide who deserves attention first.
Lead scoring declined from its May high through September before an October recovery; share is up 27.1% over the last 30 days but remains down over 90 days. No single launch explains the curve. The recurring thread is execution: persona-specific qualification, AI-assisted prioritization, and ABM systems that get intent signals into the CRM before reps miss the moment.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Clay | 93 |
| 3 | Instantly | 66 |
| 4 | Claude Code | 99 |
| 5 | Salesforce | 94 |
| 6 | Lemlist | 49 |
| 7 | Codex | 82 |
| 8 | HeyReach | 55 |
| 9 | AI Ark | 48 |
| 10 | n8n | 58 |
How sales leaders hire, organize, coach and manage teams against a revenue target.
Sales leadership’s share dropped sharply in June, paused in July and declined through October; the last 30 days are down 19.9%. No single event explains the erosion, but the posts show competing approaches to staffing: Replit wants leaders who execute, Collin Cadmus advocates longer rep tenure, and a November SaaStr post introduces a Vercel discussion about going from ten SDRs to one.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Salesforce | 94 |
| 3 | Clay | 93 |
| 4 | Gong | 62 |
| 5 | Grok Bot | 76 |
| 6 | Vercel | 60 |
| 7 | Attio | 51 |
| 8 | BetterContact | 44 |
| 9 | Demandbase | 35 |
| 10 | PandaDoc | 33 |
Training, coaching, playbooks and content that help sales reps perform better.
Sales enablement fell from its July high into September, then recovered in October; the last 30 days are up 12.1%. The posts support a recurring fundamentals argument rather than a single launch explanation: Jen Allen-Knuth and Gal Aga call out training gaps, while Todd Busler’s October post presses leaders to coach reps and advance deals.
Posts to understand this · as of Nov 5
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | HubSpot | 89 |
| 3 | Claude Code | 99 |
| 4 | Gong | 62 |
| 5 |  Highspot | 30 |
| 6 | Salesforce | 94 |
| 7 |  Seismic | 29 |
| 8 | BetterContact | 44 |
| 9 | Cursor (Anysphere) | 75 |
| 10 | Monaco | 30 |
A discipline built around experiments, channels and loops that drive efficient growth.
Growth marketing fell after May, recovered some ground in September, and is now down 9.5% over the last 30 days. No single event explains the curve; the recurring debate is how much channel work becomes GTM engineering. Clay Ads supplies an automation example, while Anthropic’s October hiring post keeps performance, lifecycle and SEO in the remit.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Claude Code | 99 |
| 3 | Optimizely | 33 |
| 4 | HubSpot | 89 |
| 5 | Webflow | 48 |
| 6 | Primer | 32 |
| 7 | Grok Bot | 76 |
| 8 | Ploy | 31 |
| 9 | Codex | 82 |
| 10 | Ahrefs | 50 |
Command-line tools that let people and agents run go-to-market work without a dashboard.
CLIs for GTM more than doubled from April to a July high of 1.25%, the month Clay shipped its API and CLI. Alex Vacca's May post on running $200k a month in ads from a terminal came first. Share cooled to 0.64% in October and is down 12.2% over 30 days, even as Alex Fine builds campaigns without opening Clay.
Posts to understand this · as of Nov 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 93 |
| 3 | HubSpot | 89 |
| 4 | Instantly | 66 |
| 5 | Exa.ai | 51 |
| 6 | Grok Bot | 76 |
| 7 | HeyReach | 55 |
| 8 | Salesforce | 94 |
| 9 | n8n | 58 |
| 10 | Apify | 54 |
Reusable instructions that teach an agent how to complete a specific kind of task.
Agent Skills peaked at 1.67% in May and fell to about 0.7% by October, down 36.3% over 90 days. No single event explains the slide. The last 30 days are down 7.9%, and the posts have turned practical: Luke Harries shares an OKR review skill, and Alex Fine runs outbound from Claude Code.
Posts to understand this · as of Nov 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 93 |
| 3 | Codex | 82 |
| 4 | HubSpot | 89 |
| 5 | Cursor (Anysphere) | 75 |
| 6 | HeyReach | 55 |
| 7 | Apify | 54 |
| 8 | Instantly | 66 |
| 9 | Salesforce | 94 |
| 10 | n8n | 58 |
The software stack marketers use to plan, run, measure and improve their work.
Martech lost share after May, with an August bounce that did not hold through October; the last 30 days are up 10.1%. The posts frame a continuing debate over stack complexity rather than a single launch: Scott Brinker proposes a unified data foundation, Joe Chernov warns about agent sprawl, and May Habib argues watermarking belongs in enterprise procurement.
Posts to understand this · as of Nov 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 89 |
| 3 | Braze | 39 |
| 4 | GrowthLoop | 29 |
| 5 | G2 | 58 |
| 6 | ZoomInfo | 52 |
| 7 | Clay | 93 |
| 8 |  Hightouch | 32 |
| 9 | Influ2 | 28 |
| 10 |  MoEngage | 24 |
Founders, executives and employees using their own voices to distribute the company's ideas.
Conversation held near 1% from April through August, fell in September, then partially recovered in October; the last 30 days are down 9.5%. The recurring case is personal distribution with measurable business results, exemplified by Clay’s reported 4,756 livestream registrations. October posts extend that discussion from Wispr Flow’s founder content to the limits of relying on one person.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Clay | 93 |
| 3 | Claude Code | 99 |
| 4 | Instantly | 66 |
| 5 | RB2B | 50 |
| 6 | HeyReach | 55 |
| 7 | Nooks | 48 |
| 8 | Apify | 54 |
| 9 | Profound | 52 |
| 10 | AirOps | 41 |
Growing through partners, channels, co-marketing, co-selling, resellers and other shared routes to market.
Partner marketing moved into a higher band in August and held it through October, with share up 28.8% over the last 30 days and 37.0% over 90 days. The evidence shows repeated program launches rather than one isolated announcement: OpenAI’s cyber partners, Lovable’s agency tracks, and Sierra’s ecosystem each create routes to customers through other businesses.
Posts to understand this
 inEcosystem launchSierra introduces an ecosystem of technology platforms, marketplaces, and service partnersO
 inCyber partnershipsOpenAI expands Daybreak with a program for over twenty security companiesL
 inAgency programLovable launches partner tracks with certification, directory access, and referral earnings
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Clay | 93 |
| 3 | Salesforce | 94 |
| 4 | Gong | 62 |
| 5 | HeyReach | 55 |
| 6 | Instantly | 66 |
| 7 | BetterContact | 44 |
| 8 | Claude Code | 99 |
| 9 | Findymail | 45 |
| 10 | Lovable | 60 |
The SDR and BDR function that creates pipeline through prospecting and outreach.
Sales Development peaked in May, then fell about two thirds by September. June posts put AI in the job: Notion asked SDR and BDR applicants for an agent, not a resume, and Elric Legloire tied Owner's BDR gains to one team owning AI. Share is up about 50% over 30 days; an October post scheduled an AMA for SDR leaders, but no single post explains the rise.
Posts to understand this · as of Nov 4
 inAgent applicationNotion asked SDR and BDR applicants to build an agent instead of sending a resume.EL
 inOwner's AI ownershipBreaks down how Owner reached $120k monthly per BDR with one team owning AI.BL
 inOctober AMAAnnounces a scheduled live AMA where two sales development heads will take SDR leaders' questions.
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Salesforce | 94 |
| 3 | Clay | 93 |
| 4 |  Outreach | 43 |
| 5 | Exa.ai | 51 |
| 6 | Gong | 62 |
| 7 | Influ2 | 28 |
| 8 | Monaco | 30 |
| 9 | Vercel | 60 |
| 10 | Claude Code | 99 |
The team that owns marketing systems, campaign execution, data and reporting.
Marketing operations lost conversation share from April through September, with an August bump, then recovered modestly in October; the last 30 days are up 13.3%. Recent posts focus on who builds and owns the systems: Refine Labs acquired operations expertise, OpenAI advertised an APAC operations lead, and Ashley Faus challenged expectations that every marketer should build tools.
Posts to understand this · as of Nov 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 89 |
| 3 | Clay | 93 |
| 4 | GrowthLoop | 29 |
| 5 | Claude Code | 99 |
| 6 | ZoomInfo | 52 |
| 7 | Conversion | 28 |
| 8 | Vercel | 60 |
| 9 |  Customer.io | 37 |
| 10 | Docket | 33 |
Writing designed to persuade someone to click, reply, sign up or buy.
Copywriting climbed to a June high, then declined each month through October; the L30 move remains negative at -10.5%. No single post explains the turn, but the evidence shares a pattern: copy becomes one part of a broader GTM workflow. Claude Code handles campaigns, Corey Haines puts offers before headlines, and Nolan Ong pairs copy judgment with list quality.
Posts to understand this · as of Nov 5
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 93 |
| 3 | HubSpot | 89 |
| 4 | n8n | 58 |
| 5 | HeyReach | 55 |
| 6 | Instantly | 66 |
| 7 | Gong | 62 |
| 8 | AI Ark | 48 |
| 9 | BetterContact | 44 |
| 10 | Salesforce | 94 |
Pricing based on what a customer uses, such as credits, tokens or transactions.
May’s high coincided with concrete pricing changes: ElevenLabs introduced pay-as-you-go alongside price cuts, and monday.com launched its credit model. Share settled lower from July through September before October’s lift; the last 30 days are up 15.7%. The recent Databricks discussion adds operating experience to the conversation, though it does not establish a single cause for renewed attention.
Posts to understand this · as of Nov 8
 XPricing launchElevenLabs lowers developer prices and introduces pay-as-you-go for API and agentsSB
 inOperator perspectiveSam Blond highlights Databricks CRO Ron Gabrisko’s lessons in usage pricingRL
 inRollout breakdownRob Litterst traces monday.com’s credit model from free allowances to paid expansion
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | Clay | 93 |
| 4 | HubSpot | 89 |
| 5 | Gong | 62 |
| 6 | Exa.ai | 51 |
| 7 | ZoomInfo | 52 |
| 8 | Cursor (Anysphere) | 75 |
| 9 | Codex | 82 |
| 10 | OpenRouter | 53 |
AI agents that discover, compare and buy products on a person's behalf.
Agents as buyers stayed small through summer, then gained share in September and October; the last 30 days are up 12.9%. Concrete checkout news supports that rise: Shopify partnered with Muse, and Claude Duet adopted Link’s agent wallet. Tom Fishburne’s marketing critique shows the conversation also extends to how brands address an agent shopper.
Posts to understand this · as of Nov 7
| Brand | GTM Index | |
|---|---|---|
| 1 | Grok Bot | 76 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 94 |
| 4 | 1mind | 36 |
| 5 | Cline | 31 |
| 6 | OpenRouter | 53 |
| 7 | Profound | 52 |
| 8 | Semrush | 46 |
| 9 | ZoomInfo | 52 |
| 10 | Ahrefs | 50 |
AI agents that create, launch, buy and optimize advertising.
AI-driven advertising rose steadily from April through August, paused in September, then reached a higher share in October; the last 30 days are up 3.5%. The posts trace a practical progression: AirOps support for self-serve ChatGPT ads, agents producing ad variants, and Roadway demonstrations of campaign setup and optimization. Repeated execution examples fit the sustained rise better than one isolated announcement.
Posts to understand this · as of Nov 7
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | AirOps | 41 |
| 3 | Claude Code | 99 |
| 4 | Codex | 82 |
| 5 | Primer | 32 |
| 6 | Salesforce | 94 |
| 7 | Similarweb | 32 |
| 8 | Zapier | 52 |
| 9 | n8n | 58 |
| 10 | 6sense | 46 |
Agents that prospect, enrich data, send outreach and update revenue systems.
Revenue agents lost share every month from April through October, with only a modest +4.1% L30 move now. Persana joining forces with Rox and September’s Ami launch did not produce a sustained monthly rise. The posts trace a shift in the pitch: Ami’s founder acknowledges failed outbound fundamentals, while Nooks emphasizes agents beside reps and reports customer pipeline gains.
Posts to understand this · as of Nov 5
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Nooks | 48 |
| 3 | Salesforce | 94 |
| 4 | Exa.ai | 51 |
| 5 | HubSpot | 89 |
| 6 | Claude Code | 99 |
| 7 | Vercel | 60 |
| 8 | Sumble | 35 |
| 9 |  Attention | 27 |
| 10 | Lovable | 60 |
The point where a product solves a real need for a market that will buy it.
Product-market fit declined from April through July, then settled into a lower August-to-October plateau; the last 30 days are down 19.5%. The posts offer competing tests of fit rather than one event behind the decline: repeated validation at Lovable, different assumptions for capital-intensive startups, and Rahul Jain’s evidence of paying customers and profit.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Grok Bot | 76 |
| 3 | HubSpot | 89 |
| 4 | Viktor | 36 |
| 5 | Attio | 51 |
| 6 | Clay | 93 |
| 7 | Gamma | 45 |
| 8 | Granola | 53 |
| 9 | Lemlist | 49 |
| 10 | Primer | 32 |
How marketing teams use AI, where it helps and how it changes the job.
AI in Marketing settled into a recurring band after April’s high, with no single launch behind the pattern. Google’s marketing engineer hire, Andy Mowat’s move to Inflection, and criticism of unchanged marketing processes keep the discussion focused on roles and workflows. Share is down 27.2% over the last 30 days, despite the higher early November reading.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Grok Bot | 76 |
| 3 | Salesforce | 94 |
| 4 | Clay | 93 |
| 5 | Ahrefs | 50 |
| 6 | Braze | 39 |
| 7 | Canva | 51 |
| 8 | Chili Piper | 37 |
| 9 |  Composio | 29 |
| 10 | Cursor (Anysphere) | 75 |
Companies that reorganize how they work around AI instead of stopping at a few AI features.
An April high faded into a summer pause, then declined again through October; the last 30 days remain down 3.3%. No single event explains the shape. The posts connect AI adoption to harder organizational questions: Yamini Rangan calls for measurable process redesign, Stevie Case describes AI-native companies rebuilding classic GTM teams, and Kyle Lacy questions how careers keep pace.
Posts to understand this · as of Nov 7
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Cursor (Anysphere) | 75 |
| 3 | HubSpot | 89 |
| 4 | Claude Code | 99 |
| 5 | ElevenLabs | 56 |
| 6 |  Lorikeet | 20 |
| 7 | Primer | 32 |
| 8 | Salesforce | 94 |
| 9 | Baseten | 43 |
| 10 | Codex | 82 |
Rules, triggers and workflows that execute marketing programs across systems.
Marketing automation recovered from its June low, then held near 0.6% of conversation from July through October; the last 30 days are down just 3.7%. The evidence shows a recurring tension rather than a single catalyst: Jev promises faster ad workflows, while customer pressure and disconnected data expose the limits of automation.
Posts to understand this · as of Nov 6
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Salesforce | 94 |
| 3 | Braze | 39 |
| 4 | Clay | 93 |
| 5 | Claude Code | 99 |
| 6 | Apollo.io | 48 |
| 7 |  Klaviyo | 39 |
| 8 | Nooks | 48 |
| 9 | n8n | 58 |
| 10 |  ActiveCampaign | 30 |
Websites and docs structured so AI crawlers and agents can read and use them.
Conversation share faded through September, recovered in October, and is up 45.3% over the last 30 days. The evidence points to a recurring argument over what makes content usable by AI: Webflow reported conversion gains, Google’s guidance drew pushback, and Tim Soulo documented growing searches for agent optimization tactics whose value remains disputed.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | G2 | 58 |
| 2 | Profound | 52 |
| 3 | Claude Code | 99 |
| 4 | Grok Bot | 76 |
| 5 | Ahrefs | 50 |
| 6 | Semrush | 46 |
| 7 | Vercel | 60 |
| 8 | AirOps | 41 |
| 9 | HubSpot | 89 |
| 10 | Peec AI | 29 |
The territories, quotas, compensation plans, capacity models and reporting behind a sales organization.
Sales ops lost conversation share after May and is down 28.4% over 90 days, although the last 30 days are essentially flat at plus 1%. No discrete event explains the decline; the posts concentrate on compensation design and credibility, from SDR incentives tied to closed revenue to quota promises and seven-figure earnings at private companies.
Posts to understand this · as of Nov 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 93 |
| 3 | Claude Code | 99 |
| 4 | Gong | 62 |
| 5 | Codex | 82 |
| 6 | Exa.ai | 51 |
| 7 | Nooks | 48 |
| 8 | Cursor (Anysphere) | 75 |
| 9 | Devin | 38 |
| 10 | Grok Bot | 76 |
The work of earning awareness, trust and preference for a company over time.
Brand Building dropped sharply in September and stayed near that level in October, though the last 30 days are up 17.2%. No single event explains the drop; the recurring tension is how to defend brand budgets when attribution misses their contribution. Fin’s awareness result, Ramp’s attribution doubts and Peep Laja’s buyer-survey approach keep the conversation focused on evidence beyond credited conversions.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Gong | 62 |
| 3 | HubSpot | 89 |
| 4 | Primer | 32 |
| 5 | Profound | 52 |
| 6 | SparkToro | 29 |
| 7 | Supabase | 50 |
| 8 | Vercel | 60 |
| 9 | Ahrefs | 50 |
| 10 | AirOps | 41 |
A shared revenue knowledge layer that people and agents can query and update.
GTM Brain has moved in waves since its June high, with an October rebound and a modest 3.8% gain over the last 30 days. October’s posts give that rebound a concrete theme: ZoomInfo bought Workbounce, Ariel Cohen demonstrated shared memory in Swan AI, and Brendan Short argued for a common context layer across revenue teams.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 94 |
| 4 | HubSpot | 89 |
| 5 | ZoomInfo | 52 |
| 6 | Exa.ai | 51 |
| 7 | Prospeo | 54 |
| 8 | Attio | 51 |
| 9 | Codex | 82 |
| 10 | Grok Bot | 76 |
Deciding what to build, why it matters and which product bets come first.
Product strategy’s May spike gave way to a steadier July-to-October band, with the last 30 days up 19.6%. The evidence spans two recurring questions: which capabilities companies should buy, and who gets to shape the roadmap. Automation Anywhere’s October agreement to acquire boost.ai adds a concrete expansion into customer-facing conversational and voice AI.
Posts to understand this
 inAcquisition strategyAutomation Anywhere agrees to acquire boost.ai for customer-facing conversational AIT
 inRole definitionTamara Grominsky separates upstream product marketing from downstream executionAA
 inOrganizational critiqueAatir Abdul Rauf describes organizations that exclude PMMs from strategic work
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Clay | 93 |
| 3 | Salesforce | 94 |
| 4 | Claude Code | 99 |
| 5 | Exa.ai | 51 |
| 6 | OpenRouter | 53 |
| 7 | Apify | 54 |
| 8 | Resend | 32 |
| 9 | Vercel | 60 |
| 10 | ZoomInfo | 52 |
Business software that exposes data and actions through APIs, MCP and command-line tools.
Salesforce’s April Headless 360 reveal anchors the strongest month, with APIs, MCP and CLI access across its platforms. Share then fell through July, recovered through September and slipped in October; the last 30 days are down 36.7%. Glean’s October workflow provides a concrete developer use case, but no comparable broad announcement explains the later recovery.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | Clay | 93 |
| 4 | HubSpot | 89 |
| 5 | ZoomInfo | 52 |
| 6 | Apify | 54 |
| 7 | Vercel | 60 |
| 8 | Braze | 39 |
| 9 | Cursor (Anysphere) | 75 |
| 10 | Exa.ai | 51 |
Buying, onboarding and expanding inside a product without talking to a salesperson.
Self-Serve held flat in July and August before losing share through October; the last 30 days show a modest 4.3% lift. The plateau contains competing stories: Metronome opened self-serve access, while Elena Verna used the reported Airtable deal to question enterprise expansion at self-serve’s expense. Cargo’s October account adds another constraint: customers may need help designing what they want to build.
Posts to understand this · as of Nov 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Salesforce | 94 |
| 3 | HubSpot | 89 |
| 4 | Claude Code | 99 |
| 5 | Apify | 54 |
| 6 | Exa.ai | 51 |
| 7 | FullEnrich | 45 |
| 8 | Gong | 62 |
| 9 | OpenRouter | 53 |
| 10 | ZoomInfo | 52 |
Teams building internal software with AI instead of buying another SaaS product.
Replacing SaaS with internal tools has lost share since April, with a brief July rebound and another drop in October; the last 30 days are down 29.2%. The posts consistently challenge blanket replacement: Slack and Granola examples emphasize maintenance and opportunity cost, while Frans Riemersma describes a mix of SaaS augmentation, AI-native products, and selective internal builds.
Posts to understand this · as of Nov 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | HubSpot | 89 |
| 3 | Salesforce | 94 |
| 4 | Vercel | 60 |
| 5 | Apify | 54 |
| 6 | Exa.ai | 51 |
| 7 | ZoomInfo | 52 |
| 8 | OpenRouter | 53 |
| 9 | Resend | 32 |
| 10 | Claude Code | 99 |
Tracing and monitoring what a model or agent did during a production run.
Observability rose from a fairly steady June and July base into September, then eased in October; the last 30 days are down 4.4%, despite a 20% gain over 90 days. The recurring demand is visibility and control without extra vendor burden. Intercom’s Fin suite, CrewAI’s bank sales experience and Gartner’s November commentary connect the topic to product features, procurement and governance.
Posts to understand this · as of Nov 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | LangChain | 45 |
| 3 | Codex | 82 |
| 4 | HubSpot | 89 |
| 5 | Midjourney | 33 |
| 6 | Vercel | 60 |
| 7 | Attio | 51 |
| 8 | Baseten | 43 |
| 9 | Clay | 93 |
| 10 |  CrewAI | 25 |
Using dinners, meetups, conferences and field events to build demand and trust in person.
Events conversation has been choppy, with stronger May, July and October shares rather than a sustained climb; the last 30 days are down 16.1%. No single conference explains those waves. The recurring argument is specific, personal contact: Sequel.io’s CMO dinners, event-based outreach, and Morgan J Ingram’s account of sellers returning to face-to-face meetings.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Salesforce | 94 |
| 3 | HubSpot | 89 |
| 4 | Lovable | 60 |
| 5 |  Aurasell | 16 |
| 6 | Primer | 32 |
| 7 | Vercel | 60 |
| 8 | Webflow | 48 |
| 9 | Ahrefs | 50 |
| 10 | Apify | 54 |
The software stack sales teams use to prospect, engage buyers and manage deals.
Sales Tech lost share through September, steadied in October and is up 10.9% over the last 30 days. The posts point to a recurring concern rather than one catalyst: agents need usable data and better judgment, not just more activity. Airscale’s API, an ill-timed Oracle cold call and a Clay-centered workflow put that concern in concrete terms.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Clay | 93 |
| 3 | HubSpot | 89 |
| 4 | Claude Code | 99 |
| 5 | ZoomInfo | 52 |
| 6 | Gong | 62 |
| 7 |  Lightfield | 28 |
| 8 | Nooks | 48 |
| 9 | OpenRouter | 53 |
| 10 | Outreach | 43 |
The tools, data and workflows that turn outbound sales into a repeatable operating system.
Outbound systems peaked in May and lost share every completed month afterward, with the last 30 days down another 21.1%. The posts show automation examples without sustained conversation growth: Docebo’s UserGems workflow and gtmskills.com’s free outbound skills. By October, Raouf Lemouchi offered a contrasting example of café sales built on visits, product knowledge and direct contact.
Posts to understand this · as of Nov 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | HubSpot | 89 |
| 3 | Claude Code | 99 |
| 4 | Salesforce | 94 |
| 5 | HeyReach | 55 |
| 6 | Instantly | 66 |
| 7 | RB2B | 50 |
| 8 | Grok Bot | 76 |
| 9 | Smartlead | 45 |
| 10 | AI Ark | 48 |
Protecting models and agents from prompt injection, data leaks, unsafe access and attacks.
AI security held relatively steady from May through August, dropped in September, and recovered some ground in October; the last 30 days are up 8.4%, against a 42.1% decline over 90 days. Vanta’s growth story and OpenAI’s GPT-Red announcement anchor the earlier discussion. Dust’s November Datadog AI Guard beta adds a concrete example of checks inside agent workflows.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 82 |
| 3 | Midjourney | 33 |
| 4 | Attio | 51 |
| 5 | Cursor (Anysphere) | 75 |
| 6 | ElevenLabs | 56 |
| 7 | Firecrawl | 41 |
| 8 | Hightouch | 32 |
| 9 |  Pitch | 17 |
| 10 | Runway | 36 |
Using AI to tailor outreach and marketing to each person at scale.
Share declined from April into a September–October plateau, while the last 30 days show a 41.2% recovery. The recurring thread is dissatisfaction with superficial personalization: Kyle Asay used AI to narrow accounts, Nick Palasz argued for relevance over observations, and Kelly Jo Horton praised Chewy’s human service. Renewed attention includes criticism of automation, not just adoption.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Salesforce | 94 |
| 3 | Claude Code | 99 |
| 4 | HubSpot | 89 |
| 5 | Vercel | 60 |
| 6 | Exa.ai | 51 |
| 7 | Gong | 62 |
| 8 | Grok Bot | 76 |
| 9 | Lemlist | 49 |
| 10 | Prospeo | 54 |
Multi-step work planned and executed by agents instead of fixed automation rules.
Agentic workflows peaked in May, softened through August and bounced in September before another October decline; the last 30 days are down 30.1%. Practical examples recur across the period, from Dave Steer’s reporting workflow to Clay’s global agent and Aurasell’s sales results. October’s product news and operating claims did not sustain September’s share, and no single post explains both spikes.
Posts to understand this · as of Nov 6
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 94 |
| 4 | Instantly | 66 |
| 5 | AI Ark | 48 |
| 6 | Clay | 93 |
| 7 | Codex | 82 |
| 8 | Exa.ai | 51 |
| 9 | Findymail | 45 |
| 10 | HeyReach | 55 |
Salesforce's annual flagship conference, where the company and its ecosystem unveil products and court customers.
Dreamforce shows a conference-shaped spike: almost absent in spring, higher in August, then at 3.7% in September before a sharp October drop. Salesforce’s Anthropic partnership promotion, Informatica’s debut as part of Salesforce and debate over conference ROI all cluster in September. The last 30 days are down 87.8%, consistent with that concentrated event cycle.
Posts to understand this · as of Nov 7
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 89 |
| 3 | Clay | 93 |
| 4 | 1mind | 36 |
| 5 | ZoomInfo | 52 |
| 6 | 11x | 24 |
| 7 |  AiSDR | 21 |
| 8 | Apify | 54 |
| 9 | Base44 | 26 |
| 10 | Braze | 39 |
Approval and review steps that keep a person involved in an agent's work.
Human in the Loop has brief May and August bumps, but neither holds; share fell through September and October, and the last 30 days are down 16.2%. The posts do not explain those bumps with a single event. Instead, oversight recurs as a practical requirement across autonomy frameworks, Tenex’s agent launch and Yahoo DSP’s discussion of trust.
Posts to understand this · as of Nov 7
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Salesforce | 94 |
| 3 | HubSpot | 89 |
| 4 | Vercel | 60 |
| 5 | Claude Code | 99 |
| 6 | Codex | 82 |
| 7 | HeyReach | 55 |
| 8 | Instantly | 66 |
| 9 | Nooks | 48 |
| 10 |  Pinecone | 32 |
Agents hired, managed and sold as named workers, from AI coworkers to digital employees.
AI employees held a fairly steady share from June through September before an October drop; the last 30 days remain down 7.8%. November’s early bar is higher, but it does not establish a recovery. The evidence moves from Vista’s digital worker thesis to a deployable Slack employee and Databricks’ governed rollout playbook, without a single event that explains the decline.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Viktor | 36 |
| 2 | HubSpot | 89 |
| 3 | Clay | 93 |
| 4 | Salesforce | 94 |
| 5 | Ploy | 31 |
| 6 | Primer | 32 |
| 7 | 6sense | 46 |
| 8 | Ahrefs | 50 |
| 9 | Apify | 54 |
| 10 | Codex | 82 |
Systems for producing and distributing large volumes of marketing content, often with AI.
Conversation share fell from May through October and is down another 19.4% over the last 30 days. The posts point to a recurring challenge to volume: Amos Bar-Joseph criticizes recognizable AI prose, while Eli Schwartz warns about Google's treatment of spam. Dima Bilous offers a practical counterpoint, with a Claude Code content system tied to booked calls.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Clay | 93 |
| 3 | G2 | 58 |
| 4 | HeyReach | 55 |
| 5 | HubSpot | 89 |
| 6 | Peec AI | 29 |
| 7 | Salesforce | 94 |
| 8 | AI Ark | 48 |
| 9 | Ahrefs | 50 |
| 10 | AirOps | 41 |
Companies reducing their go-to-market stack by replacing point tools with broader platforms.
May’s high coincided with Gong reporting more than $500 million ARR and naming point-tool consolidation as a growth driver. Conversation settled onto a lower September–October plateau, while Apollo’s complete AI GTM system supplied a fresh platform story. The last 30 days are up 3.5%, consistent with modest renewed attention around replacing disconnected tools.
Posts to understand this · as of Nov 5
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Salesforce | 94 |
| 3 | Gong | 62 |
| 4 | HubSpot | 89 |
| 5 | Clari | 32 |
| 6 | Claude Code | 99 |
| 7 |  Fathom | 34 |
| 8 | Outreach | 43 |
| 9 | Braze | 39 |
| 10 | Codex | 82 |
AI sales agents that respond to inbound interest, engage website visitors, qualify leads and connect prospects with sales teams.
Inbound agents saw a June bump around HubSpot’s announced Warmly acquisition, followed by a summer trough and recovery through September and October. Share is up 46.6% over the last 30 days; Single Grain’s October test of a voice bot that calls demo leads within 60 seconds adds a concrete workflow example, though no single event explains the recovery.
Posts to understand this · as of Nov 4
 inAcquisition announcementWarmly’s cofounder announces HubSpot’s acquisition after years of integration growthAV
 inEarlier deal contextChili Piper’s cofounder discusses Salesforce’s Qualified acquisition and inbound overlapE
 XWorkflow testSingle Grain tests a voice bot that calls demo leads within seconds
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Vercel | 60 |
| 3 | Salesforce | 94 |
| 4 | HubSpot | 89 |
| 5 | Claude Code | 99 |
| 6 |  Qualified | 28 |
| 7 | Grok Bot | 76 |
| 8 | Primer | 32 |
| 9 | ZoomInfo | 52 |
| 10 | 11x | 24 |
Founders running early sales themselves before handing the motion to a sales team.
Conversation dropped after April, rebounded in July, then eased through September before a modest October recovery. The last 30 days are down 3.1%. Kazanjy’s July post offers founders a free sales guide; later posts focus on first-rep hiring and product-market fit, with Lemkin emphasizing whom founders would buy from and Roberge examining retention.
Posts to understand this · as of Nov 4
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Claude Code | 99 |
| 3 | Clay | 93 |
| 4 | Passionfroot | 22 |
| 5 | Ploy | 31 |
| 6 | Primer | 32 |
| 7 | Sumble | 35 |
| 8 | Salesforce | 94 |
| 9 | 6sense | 46 |
| 10 |  Clarify | 29 |
Marketing to existing leads and customers through onboarding, nurture, retention and expansion programs.
After a May high and an August low, lifecycle marketing recovered modestly in September and October; its last 30 days are up 11%. The evidence points to repeated attempts to make customer outreach more useful and easier to run, rather than one catalyst. Lifecycle Studio, Customer.io's Americaneagle.com partnership and Lorikeet Dreamweaver span campaign production, data activation and individual AI account managers.
Posts to understand this
 inProduct launchLorikeet introduces Dreamweaver with an AI account manager for each customerC
 inAgency partnershipCustomer.io partners with Americaneagle.com on data activation and lifecycle messagingTM
 inCampaign workflowLifecycle Studio launches with Thumbtack reporting shorter campaign production cycles
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Salesforce | 94 |
| 3 | Clay | 93 |
| 4 | GrowthLoop | 29 |
| 5 | Supabase | 50 |
| 6 | 6sense | 46 |
| 7 | AI Ark | 48 |
| 8 | Ahrefs | 50 |
| 9 | Airtable | 42 |
| 10 | Apify | 54 |
Systems where several agents divide a job, coordinate their work and combine the result.
Share peaked in May and declined through October, with a further 62.1% drop over the last 30 days. No single event explains the slide: Workato expanded Airo, Mercor reported a 100-plus-subagent run, and ZoomInfo acquired DoubleO.ai during the decline. These posts emphasize workflow reliability and evaluation, but those concrete developments did not sustain broader conversation share.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 94 |
| 3 | HubSpot | 89 |
| 4 | Clay | 93 |
| 5 | Findymail | 45 |
| 6 | Firecrawl | 41 |
| 7 | Gong | 62 |
| 8 | Grok Bot | 76 |
| 9 | HeyReach | 55 |
| 10 | Instantly | 66 |
Writing and structuring the instructions a model follows.
Prompt engineering reached its highest monthly share in June, then declined through October; the last 30 days are down 20.3%. No single event explains that retreat, but the posts consistently question prompts as the main source of value. Carolyn Healey emphasizes context, Laurens Nys calls for agents with setup already done, and Wil Reynolds warns that polished prompts still leave recognizable patterns.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | Claude Code | 99 |
| 3 | Gong | 62 |
| 4 | HubSpot | 89 |
| 5 |  Reachdesk | 26 |
| 6 | SparkToro | 29 |
A permanently free product tier designed to attract users and convert some to paid plans.
Freemium’s August–September recovery coincided with OpenAI’s report that ChatGPT ads reached a $1 billion annualized revenue run rate to help fund free access. Share eased in October, and the last 30 days are down 45%. Across OpenAI, Fireflies, and Perplexity, the recurring thread is how free usage supports revenue through ads, paid agent work, or enterprise sales.
Posts to understand this · as of Nov 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Ahrefs | 50 |
| 2 | HubSpot | 89 |
| 3 | Claude Code | 99 |
| 4 | Canva | 51 |
| 5 | Grok Bot | 76 |
| 6 |  Pocus | 27 |
| 7 | Salesforce | 94 |
| 8 | Airtable | 42 |
| 9 | Apollo.io | 48 |
| 10 | Attio | 51 |
Choosing which model should run each task based on cost, quality, speed or risk.
Model routing climbed through summer and held near 1.1% of conversation in August and September, with Cursor’s router launch and reported Harvey margin pressure giving it concrete product and cost hooks. October broke that plateau, and the last 30 days are down 71.9%. Notion’s cheaper Auto router supplied fresh news, but did not sustain the earlier share.
Posts to understand this · as of Nov 7
| Brand | GTM Index | |
|---|---|---|
| 1 | Canva | 51 |
| 2 | Higgsfield | 41 |
| 3 | OpenRouter | 53 |
| 4 | Baseten | 43 |
| 5 | Cursor (Anysphere) | 75 |
| 6 | Lovable | 60 |
| 7 | Replit | 55 |
| 8 | Substack | 52 |
| 9 | Claude Code | 99 |
| 10 | ElevenLabs | 56 |
Advantages that grow stronger as more people, data or participants join a product.
Conversation share fell steadily from April through October; the last 30 days are up 34.7%, while the last 90 remain down 36%. April’s ecosystem discussion provides a concrete example, while Casado’s October critique questions loose definitions, including claims like Yan’s March description of usage and trust as a network effect.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Cursor (Anysphere) | 75 |
| 3 | OpenRouter | 53 |
| 4 | Replit | 55 |
| 5 | Attio | 51 |
| 6 |  BlitzAPI | 27 |
| 7 | Clay | 93 |
| 8 | ElevenLabs | 56 |
| 9 | Granola | 53 |
| 10 | Higgsfield | 41 |
Marketing inside large companies with bigger budgets, stricter governance and more complex brands.
Enterprise marketing held near its summer high in July and August, then lost share through October; the last 30 days are down 17.1%. The posts trace a recurring problem: connecting creative work, customer data and AI governance. Canva’s LinkedIn ads session and Iterable’s CustomerLake beta announcement give that discussion concrete examples, but neither explains the decline.
Posts to understand this · as of Nov 6
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Salesforce | 94 |
| 3 | AirOps | 41 |
| 4 | Aurasell | 16 |
| 5 |  Backstory | 16 |
| 6 |  Creatio | 17 |
| 7 | G2 | 58 |
| 8 | Grok Bot | 76 |
| 9 | Lightfield | 28 |
| 10 | Lovable | 60 |
Pricing tied to a delivered result, such as a resolution, meeting or completed task.
Outcome-based pricing recovered through September and October after an August low, with the last 30 days up 42%. The evidence moves from HubSpot’s explicit per-result prices and Vista’s market-expansion thesis to Intercom’s advice on forecasting spend. That practical budgeting question accompanies renewed attention, though share is still down 31.6% over 90 days.
Posts to understand this · as of Nov 7
| Brand | GTM Index | |
|---|---|---|
| 1 | Salesforce | 94 |
| 2 | HubSpot | 89 |
| 3 | Clay | 93 |
| 4 | G2 | 58 |
| 5 | Ahrefs | 50 |
| 6 | Claude Code | 99 |
| 7 | Cursor (Anysphere) | 75 |
| 8 | FullEnrich | 45 |
| 9 | Gong | 62 |
| 10 | OpenRouter | 53 |
How sales teams use AI and how it changes the work of selling.
Conversation share peaked in May, fell in June, stayed flat in July, then declined through October. The last 30 days are nearly flat, up 1%. Selected posts span June’s push to hire AI-fluent sellers, October’s account of workflow adoption problems, and November’s criticism of hours saved as a measure of revenue impact.
Posts to understand this · as of Nov 9
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Salesforce | 94 |
| 3 | Cursor (Anysphere) | 75 |
| 4 | Lovable | 60 |
| 5 | Codex | 82 |
| 6 | Monaco | 30 |
| 7 |  Mutiny | 31 |
| 8 | 11x | 24 |
| 9 | Apollo.io | 48 |
| 10 | Attio | 51 |
The sameness that appears when AI gives every company similar messaging, claims and websites.
Conversation share declined every month from April through October, though the last 30 days are up 4.3%. The posts show a recurring complaint rather than one event: AI content lacks customer context and a point of view. Diandra Escobar’s Claude hook skill adds a practical response to the sameness critique, with explicit rules and real examples.
Posts to understand this · as of Nov 7
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Primer | 32 |
| 3 | Substack | 52 |
| 4 | Apify | 54 |
| 5 | Claude Code | 99 |
| 6 | Exa.ai | 51 |
| 7 | Grok Bot | 76 |
| 8 | HubSpot | 89 |
| 9 | PandaDoc | 33 |
| 10 | Profound | 52 |
The online channel mix used to reach, convert and retain customers.
Digital marketing rebounded in October after three months of decline, with conversation share up 148.3% over the last 30 days. The evidence points to a recurring systems theme rather than one trigger: Ahrefs offered Agent A trials in May, workflows.io mapped multichannel funnels in September, and EasyVista connected SEO, AI visibility, paid media and automation in early November.
Posts to understand this · as of Nov 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Ahrefs | 50 |
| 3 | AirOps | 41 |
| 4 | Monaco | 30 |
| 5 | Semrush | 46 |
| 6 | Apollo.io | 48 |
| 7 | Baseten | 43 |
| 8 | Claude Code | 99 |
| 9 | Codex | 82 |
| 10 | Cursor (Anysphere) | 75 |
The strategy of naming, defining and leading a new market.
Category creation held near 0.4% share from April through June, then became uneven before a September drop; the last 30 days are up a modest 4.5%. The posts reveal a consistent skepticism about category names without buyer demand. Rob Kaminski stresses the job to be done, Joe Chernov questions AI-era category creation, and Peep Laja sets conditions for an AI pivot.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Clay | 93 |
| 3 | Gong | 62 |
| 4 | AppsFlyer | 19 |
| 5 |  Bland | 18 |
| 6 | Braze | 39 |
| 7 | Canva | 51 |
| 8 |  Docusign | 31 |
| 9 | Hightouch | 32 |
| 10 |  Manychat | 18 |
AI-generated creators, avatars and user-style content used in marketing.
Conversation share shrank from 0.36% in April to 0.09% in August, then recovered partly in September alongside HeyGen’s research on unpublished business videos. The last 30 days are flat, so the recovery has not become sustained acceleration. The recurring tension is practical production help versus authenticity, visible in Corey Haines’ tooling and alinav’s avatar critique.
Posts to understand this · as of Nov 9
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | HeyGen | 33 |
| 3 | Instantly | 66 |
| 4 | Apify | 54 |
| 5 | Exa.ai | 51 |
| 6 | People Data Labs | 24 |
| 7 | AppsFlyer | 19 |
| 8 | Clay | 93 |
| 9 |  Framer | 28 |
| 10 | Gamma | 45 |
Companies run mostly by AI agents with few or no people, measured in revenue per employee.
Autonomous business reached its strongest month in May, when Polsia’s reported $10 million run rate and $30 million fundraise supplied a concrete one-employee story, then faded through August. Conversation is up 45.2% over the last 30 days, with Swan AI’s workflow counts and Andrew Chen’s founder debate replacing headline scale with questions about what small teams can actually handle.
Posts to understand this · as of Nov 5
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Lovable | 60 |
| 3 | Base44 | 26 |
| 4 | Canva | 51 |
| 5 | Codex | 82 |
| 6 | Cursor (Anysphere) | 75 |
| 7 | G2 | 58 |
| 8 | Grok Bot | 76 |
| 9 | Salesforce | 94 |
| 10 |  Twilio | 43 |
Time-limited access that lets a buyer test a product before paying.
Share rose from April through July, then lost ground unevenly; the last 30 days are down 25.1%. No launch explains the curve. The posts instead revisit practical conversion problems: funnel benchmarks, compensation rules that delayed trial outreach, and Sunsama’s offer to restart an underused trial, a useful October example that did not coincide with a broader recovery.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Clay | 93 |
| 3 | AI Ark | 48 |
| 4 | Canva | 51 |
| 5 | Claude Code | 99 |
| 6 |  Fibbler | 35 |
| 7 |  Freckle.io | 32 |
| 8 | G2 | 58 |
| 9 | Gong | 62 |
| 10 | Intercom | 43 |
Independent advisors and fractional executives selling experience, judgment and hands-on help.
Advisory’s April high coincided with GTMEE’s launch and a case for long-term fractional CMOs, then share stepped down to a smaller range through October. The last 30 days are down 12.5%. November’s fractional CRO pitch returns to the same cost, speed, and experience arguments: a recurring commercial case, with no single event that explains the decline.
Posts to understand this · as of Nov 9
| Brand | GTM Index | |
|---|---|---|
| 1 | AirOps | 41 |
| 2 | Consensus | 26 |
| 3 |  Factors.ai | 21 |
| 4 | Gamma | 45 |
| 5 | Gong | 62 |
| 6 | Highspot | 30 |
| 7 | HubSpot | 89 |
| 8 | Lovable | 60 |
| 9 | Profound | 52 |
| 10 | Salesforce | 94 |
Go-to-market teams designed around AI from the start, with different roles, costs and speed.
AI-Native GTM spiked in May, the month Kyle Norton's Replit conversation argued for building workflows, buying plumbing and still hiring reps. June fell back below April, and share has mostly drifted down since, with the last 30 days off 30%. October's posts treat it as a job and a buying category, with Justin Norris joining Zendesk and Attention citing Ramp data.
Posts to understand this · as of Nov 4
| Brand | GTM Index | |
|---|---|---|
| 1 | Nooks | 48 |
| 2 | Aurasell | 16 |
| 3 | Clay | 93 |
| 4 | Lightfield | 28 |
| 5 | Lovable | 60 |
| 6 | Monaco | 30 |
| 7 | OpenRouter | 53 |
| 8 | Replit | 55 |
| 9 | Salesforce | 94 |
| 10 | Sumble | 35 |
How AI changes headcount, entry-level work and the jobs people still need to do.
Conversation share peaked in May, then settled into a lower range from July through October; the last 30 days are down 33.6%. May’s OpenAI SDR hiring example challenged replacement claims, while later posts paired small-team revenue stories with proposals for redesigned GTM roles. The pattern is a recurring debate over which tasks move to AI and which remain human.
Posts to understand this · as of Nov 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | HubSpot | 89 |
| 3 | 11x | 24 |
| 4 | 1mind | 36 |
| 5 | Ahrefs | 50 |
| 6 | Conversion | 28 |
| 7 | Docket | 33 |
| 8 | ElevenLabs | 56 |
| 9 | Framer | 28 |
| 10 | FullEnrich | 45 |
The runtime around an agent that provides tools, state, controls and stopping rules.
Agent harnesses show bursts rather than a sustained climb: June was highest, August rebounded, and September and October declined. DeepSeek’s Harness preview and Cloudflare’s computer runtime give August’s rebound concrete launch context; September brought a GTM explainer from Scott Martinis. That sequence moved from releases to explanation without sustained share, and the last 30 days are down 59.8%.
Posts to understand this · as of Nov 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Salesforce | 94 |
| 3 | Attio | 51 |
| 4 | Codex | 82 |
| 5 | Cursor (Anysphere) | 75 |
| 6 | HubSpot | 89 |
| 7 | LangChain | 45 |
AI-native firms that sell finished work instead of software, delivered by agents and a small human team.
Services-as-Software held its spring high in May and June, then settled into a lower band from July through October; the last 30 days are flat. The evidence moves from Emergence’s outcome-based services thesis and Daydream’s $15 million Series A to Noble’s focus on operations before scale. That makes the plateau a quieter execution conversation, with no single event explaining the decline.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Findymail | 45 |
| 2 | HeyReach | 55 |
| 3 | HubSpot | 89 |
| 4 | Pinecone | 32 |
| 5 | Supabase | 50 |
| 6 | Vercel | 60 |
| 7 | n8n | 58 |
| 8 | AI Ark | 48 |
| 9 | Airtable | 42 |
| 10 | Apify | 54 |
Rule-based software that moves business work through predefined steps and systems.
Workflow automation’s share fell from 0.667% in April to 0.139% in October, with a small July pause; the overlapping last 30 days show a 41.1% decline. The selected posts frame workflow tools as something teams can build themselves, question brittle order-processing automation, and put enterprise governance at the center of buying decisions.
Posts to understand this · as of Nov 9
 inBuild pressureMiller argues workflow interfaces and integration glue are candidates for in-house buildsC
 inOperational frictionConexiom highlights manual purchase orders and RPA that breaks when formats changeW
 inBuying criteriaWorkato compares automation approaches around identity, governance, auditability, and scale
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | AI Ark | 48 |
| 3 | Clay | 93 |
| 4 | HubSpot | 89 |
| 5 | Instantly | 66 |
| 6 | n8n | 58 |
| 7 | Codex | 82 |
| 8 | Findymail | 45 |
| 9 | FullEnrich | 45 |
| 10 | HeyReach | 55 |
HubSpot's annual customer conference, where sales and marketing teams gather to network and learn.
The curve follows an event cycle: April’s INBOUND-to-UNBOUND rename produced an initial burst, followed by a summer buildup and September spike around the Boston conference. Partner Day and a discussion with Anthropic supplied concrete September material. October’s drop and the 88.8% decline over the last 30 days fit attention receding after the event.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | 1mind | 36 |
| 3 | Ahrefs | 50 |
| 4 | AirOps | 41 |
| 5 | Apify | 54 |
| 6 | AthenaHQ | 20 |
| 7 | Base44 | 26 |
| 8 |  Breeze | 23 |
| 9 | Docket | 33 |
| 10 | Exa.ai | 51 |
Software designed for agents to operate as the primary user.
From almost no conversation in spring, share built unevenly through October and is up 85.1% over the last 30 days. The posts give that rise a concrete pattern: Lorikeet launched agent traffic detection, Melissa Rosenthal examined access restrictions at Amazon and Cloudflare, and Tealium argued for agent-ready data layers. Agent visits are becoming an operational and commercial question.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Attio | 51 |
| 2 | Claude Code | 99 |
| 3 | Midjourney | 33 |
| 4 | Cursor (Anysphere) | 75 |
| 5 | Grok Bot | 76 |
| 6 | Replit | 55 |
| 7 | Vercel | 60 |
| 8 | Ahrefs | 50 |
| 9 | Base44 | 26 |
| 10 | Canva | 51 |
Products distributed as apps or connectors inside AI assistants and agent marketplaces.
A steady June-to-August plateau gave way to sharp September and October declines, with the last 30 days down 15.8%. The meaningful pattern is that concrete connector releases continued even as conversation share shrank: Zapier brought thousands of tools to Claude for Small Business, and AthenaHQ added an official Claude connector. Those announcements did not sustain the summer share.
Posts to understand this
| Brand | GTM Index | |
|---|---|---|
| 1 | Cursor (Anysphere) | 75 |
| 2 | Claude Code | 99 |
| 3 | Salesforce | 94 |
| 4 | Exa.ai | 51 |
| 5 | HubSpot | 89 |
| 6 | Canva | 51 |
| 7 |  Cartesia | 28 |
| 8 | ElevenLabs | 56 |
| 9 |  Ghost | 17 |
| 10 | Grok Bot | 76 |
The argument over requiring a form before someone can access useful content.
Gated content peaked in May alongside Amanda Natividad’s distinction between open arguments and gated utility, then declined into an August–September plateau. Conversation is up 39.8% over the last 30 days as the debate shifts toward when gates make sense and how MQL targets encourage them, rather than a single event that settles the form’s future.
Posts to understand this · as of Nov 5
| Brand | GTM Index | |
|---|---|---|
| 1 | HubSpot | 89 |
| 2 | Apify | 54 |
| 3 | Claude Code | 99 |
| 4 | Clay | 93 |
| 5 | beehiiv | 51 |
| 6 | Exa.ai | 51 |
| 7 | Nooks | 48 |
| 8 | Primer | 32 |
| 9 | Salesforce | 94 |
| 10 | Vercel | 60 |
Embedded marks and signed metadata that show where digital content came from and how it was made.
Watermarking’s outsized August spike aligns with explicit compliance announcements: Anthropic explained its watermarking plans, and Synthesia described automatic video marks and C2PA credentials. Share dropped sharply in September, then recovered modestly in October as May Habib pushed enterprise policy onto the marketing agenda. The last 30 days are down 30.5%, consistent with a burst around compliance followed by a smaller policy conversation.
Posts to understand this · as of Nov 6
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Attio | 51 |
| 3 | Canva | 51 |
| 4 | Codex | 82 |
| 5 | ElevenLabs | 56 |
| 6 | Grok Bot | 76 |
| 7 | Midjourney | 33 |
| 8 |  Riverside | 28 |
| 9 | Salesforce | 94 |
Pushback against AI from customers, workers and the public, and brands repositioning as pro-human.
AI Backlash moves in bursts. May spiked as Rand Fishkin split consumer resistance from business enthusiasm and Christopher Lochhead called the reaction dumb, and a smaller August bump faded. The last 30 days are down 47%, with Kelly Jo Horton's AI fatigue post from 6sense Breakthrough as early November context.
Posts to understand this · as of Nov 4
 inSplit marketRand Fishkin contrasts consumers souring on AI with businesses going crazy for it.KJ
 inConference fatigueKelly Jo Horton praises Brittany Hodak's human-delivered customer delight talk at 6sense Breakthrough.CL
 inCounterpunchChristopher Lochhead calls the AI backlash dumb and compares protesters to Luddites.
| Brand | GTM Index | |
|---|---|---|
| 1 | Primer | 32 |
| 2 | 11x | 24 |
| 3 | 1mind | 36 |
| 4 | 6sense | 46 |
| 5 | AiSDR | 21 |
| 6 | Apify | 54 |
| 7 | Braze | 39 |
| 8 | Claude Code | 99 |
| 9 | Clay | 93 |
| 10 | Cursor (Anysphere) | 75 |
The belief that spending more on model calls and agent work can create an advantage.
Tokenmaxxing reached its highest monthly share in July, then declined through October; it is down another 22.1% over the last 30 days. The evidence traces a consistent push toward value: Sierra advocates outcomes-based pricing, Databricks demonstrates budget controls, and Dennis Sevilla collects executive complaints about token bills. These posts explain the critique around the decline, without establishing what drove July’s high.
Posts to understand this · as of Nov 6
XPricing stanceSierra argues AI success should reflect outcomes rather than token consumptionD inBudget controlsDatabricks demonstrates token budgets, model routing, and centralized agent tracingDS
 inBuyer pressureDennis Sevilla collects executive concerns about token spending without sufficient returns
| Brand | GTM Index | |
|---|---|---|
| 1 | Claude Code | 99 |
| 2 | Codex | 82 |
| 3 | Cursor (Anysphere) | 75 |
| 4 | Devin | 38 |
| 5 | Gamma | 45 |
| 6 | Grok Bot | 76 |
| 7 | OpenRouter | 53 |
Interfaces that let agents understand and operate software built for human users.
Agent experience has had bursts of attention rather than a sustained climb, with July’s rebound followed by declines through October and a 52.1% drop over the last 30 days. The summer evidence spans agent-callable updates across GTM tools and Salesforce’s experience-layer teaser; Hightouch’s September AXO pitch added a shopping use case without a broader lift in share.
Posts to understand this · as of Nov 9
| Brand | GTM Index | |
|---|---|---|
| 1 | Resend | 32 |
| 2 | Claude Code | 99 |
| 3 | Docket | 33 |
| 4 |  Netlify | 26 |
| 5 | Salesforce | 94 |
| 6 |  StackAdapt | 24 |
| 7 | Supabase | 50 |
| 8 | beehiiv | 51 |
Adopting and operating open AI models, including their licensing, deployment options, customization and costs.
Open source AI spiked in July, then declined each month through October; the last 30 days are down 47.7%. Together AI’s RAISE Summit recap puts open inference economics in the July conversation, without establishing a single cause for the spike. Later posts move toward disputes over closed-model power and enterprise security requirements as share contracts.
Posts to understand this · as of Nov 7
| Brand | GTM Index | |
|---|---|---|
| 1 | Cline | 31 |
| 2 | Cursor (Anysphere) | 75 |
| 3 | Hermes Agent | 35 |
| 4 |  Manus | 30 |
Tools that estimate whether text was written by AI by analyzing its style and statistical patterns.
AI detection jumped in July and stayed elevated in August as posts paired AI-content prevalence estimates with scrutiny of companies that offer both generation and detection tools. Share dropped sharply in September despite Semrush’s analysis of detector-classified content and search rankings. The last 30 days are up 69.4%, but these posts do not identify a fresh trigger for that rebound.
Posts to understand this · as of Nov 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Substack | 52 |
| 2 | Fathom | 34 |
| 3 |  Grammarly | 27 |
| 4 | Lightfield | 28 |
| 5 | Replit | 55 |
Brands use human authorship and craft as a reason to trust or value their work.
Human-made claims drew separate bursts in May and July–August, from Dave Gerhardt’s case for authenticity to a marketplace of human-crafted GTM skills for agents. Attention has since thinned, down 38.7% over the last 30 days. The recurring distinction is human authorship within AI-assisted work, illustrated by an October book announcement that reserves the actual writing for its author.
Posts to understand this · as of Nov 5
| Brand | GTM Index | |
|---|---|---|
| 1 | Clay | 93 |
| 2 | Clearskies | 21 |
| 3 | Grok Bot | 76 |
| 4 | Attention | 27 |
| 5 | Clarify | 29 |
| 6 | Nooks | 48 |
| 7 | Rox | 32 |
| 8 | Sumble | 35 |
| 9 | Claude Code | 99 |
| 10 | Codex | 82 |
Marketing that builds demand through credible proof, useful work and long-term audience relationships.
Trust-based marketing remains a small, uneven conversation: June and July held higher shares, followed by alternating declines and rebounds through October. The last 30 days are up 9.4%, while the 90-day move remains negative. The recurring thread is credibility over volume, with LinkedIn's seller research adding fresh evidence to earlier arguments about audience relationships and consistent customer experiences.
Posts to understand this
The plan, act, inspect and retry cycle an agent follows until it finishes.
Agent loops reached their highest share in June, held close in July, then declined through October; the last 30 days are down another 44.4%. Palantir’s Agent Engine and Agent SDK launch and Salesforce’s focus on measurable business outcomes gave July concrete substance. October’s pitch for “loop engineering” revisits the idea, but the curve shows that advocacy has not sustained attention.
Posts to understand this · as of Nov 8
| Brand | GTM Index | |
|---|---|---|
| 1 | Replit | 55 |
| 2 | Claude Code | 99 |
| 3 | Cursor (Anysphere) | 75 |
| 4 | Salesforce | 94 |
Using product activity to identify, time and support sales opportunities.
Product-led sales shows scattered mentions rather than sustained momentum, with October near zero and the last 30 days down 82.6%. The posts suggest a shift from standalone tooling to workflows inside broader platforms: Brendan Short’s March account described Pocus joining Apollo, while August’s HubSpot build showed product usage signals supporting enterprise sales through an integrated stack.
Posts to understand this · as of Nov 9
How model costs, services and agent work put pressure on software gross margins.
This is a sparse conversation, with a brief April high of 0.031% and zero-share months in May and July. The current L30 move is down 60%, and the evidence remains split between lower AI gross margins and a services model where smaller engagements can unlock a larger market.
Posts to understand this · as of Oct 9
| Brand | GTM Index | |
|---|---|---|
| 1 |  Modal | 39 |
Claude Code is Anthropic's coding agent for writing, testing and shipping code from a terminal or IDE.
Claude Code’s share fell from April through September, recovered in October and is up 27.4% over the last 30 days. The posts offer distinct threads rather than one explanation: DeepSeek promoted discounted access and million-token context in April, a July user voiced terminal fatigue, and Vercel’s October durable-harness launch added support for agents that resume after failures.
Posts to understand this
Cursor is an AI code editor with agents that write, edit and review code.
Cursor’s August spike lines up with the close of its SpaceX acquisition and another round of attention to the $60 billion deal. That burst did not hold: share fell through September and October, and the last 30 days are down another 2.1%. The evidence points to a deal-driven spike rather than sustained product news.
Posts to understand this · as of Nov 7
Clay is a flexible data and workflow platform for enrichment, research and automated go-to-market work.
Clay’s share peaked in May, fell through September, then rebounded in October. The last 30 days are up 7.5%, though the last 90 remain down 11.1%. October examples cover Clay’s orchestration role and Eric Nowoslawski’s return alongside its revenue agent mission; November adds a practitioner’s case for Clay in complex lead searches.
Posts to understand this
n8n is an open-source workflow automation tool that combines visual steps, code and AI agents.
n8n rose through June, declined through September and recovered slightly in October; the last 30 days are down 4.4%. The evidence traces a recurring integration story, from Resend’s earlier official node to June’s verified LlamaParse node and October’s local NVIDIA setup. Those additions supply concrete reasons for discussion, but no single post explains the spring rise or the subsequent decline.
Posts to understand this
Lovable is an AI app builder that turns plain-language prompts into working software.
Lovable’s strongest month shown was April, when its KPMG alliance and Databricks integration supplied concrete enterprise news. Share then fell through July despite Vercel deployment support, before settling near 1% from August through October. The last 30 days are down 13.8%, so the later integrations have not sustained April’s level of conversation.
Posts to understand this · as of Nov 7
Replit is an AI development platform that builds, deploys and runs applications from a prompt.
Replit peaked in May, dropped in June and drifted lower after an August bounce; the last 30 days are down 14.7%. The posts show distribution and expansion rather than a catalyst for renewed growth: Linear’s earlier issue handoff, September’s London office and November’s Plaid collaboration. The London announcement coincided with a lower monthly share, so geographic expansion did not produce a visible rebound.
Posts to understand this
OpenClaw is a self-hosted agent that remembers context and works across chat apps and local tools.
OpenClaw has dropped every full month since April, from 2.4% to 0.33%, and the last 30 days are down 57%. No single event explains it; this is a long, steady fade from a high start. Peter Steinberger's February move to OpenAI predates the curve, and by October Nylas was describing OpenClaw as a name that ends security conversations.
Posts to understand this · as of Nov 4
Codex is OpenAI's coding agent for planning, writing, testing and shipping software changes.
Codex’s share rose from April to May, held near 3% through September, then fell in October. The L30 decline of 33.5% points to continued cooling. Selected posts span April’s demo-building pitch, September’s harness testing and October’s durable execution launch, but do not establish what caused the decline.
Posts to understand this · as of Nov 6
Hermes Agent is an open-source personal agent that keeps memory and learns reusable skills across tasks.
Hermes Agent’s October bounce followed four months of declining share, and the last 30 days are up 32.6%. Two October releases give that bounce a concrete backdrop: one-click installation through the Microsoft Store and Tavily web search with keyless access. The recovery remains modest against a 53.2% decline over 90 days.
Posts to understand this · as of Nov 7
Salesforce is the enterprise CRM for managing sales, service, marketing and customer data.
Salesforce’s share slipped from 4.75% in April to roughly 4% through August, then rose to 4.79% in September alongside Informatica’s Dreamforce debut. Fin’s June acquisition agreement and Braze’s October agreement bookend that bump, with October back at 4.00%. The last 30 days are down 16.3%, so the current direction is lower after September’s rebound.
Posts to understand this · as of Nov 4
HubSpot is a CRM and go-to-market platform for marketing, sales, service and content.
HubSpot’s share fell from May through August before a modest recovery in September and October; the last 30 days are up 5.3%. No supplied post explains May’s high, and the Warmly acquisition announcement did not arrest the summer slide. October’s conversation mixes layoffs with practical use, including lemlist’s Claude agents accessing HubSpot deals through MCP.
Posts to understand this · as of Nov 4
Gong records and analyzes sales conversations to improve coaching, deal execution and forecasting.
Gong’s share declined from April, then held around 1.1% from August through October; the last 30 days are down another 20.4%. Its May announcement of $500 million ARR did not interrupt the monthly decline. The other posts show a steady workflow thread, from Day AI adoption among Gong customers to Crossbeam’s combined MCP use cases, rather than a fresh attention spike.
Posts to understand this
Vercel is a platform for deploying web applications and the infrastructure used by AI agents.
Vercel’s curve is uneven: gains through June, an August spike, a September drop, then an October recovery. The last 30 days are up 23.7%, while the 90-day move is nearly flat. The posts show several distinct hooks rather than one sustained launch cycle: Grok connectors, Vercel’s Iris event agent, and open-source GTM workflows through a Vercel Eve agent.
Posts to understand this · as of Nov 7
Claude Cowork is Anthropic's general-purpose agent for research, documents and other knowledge work.
Cowork’s share fell each month from 2.36% in April to 0.34% in October, with another 35.2% decline over the last 30 days. April’s live marketing demo gave way to September’s Docusign integration and October’s email workflow example, without reversing the slide. These selections are provisional: the supplied data does not mark either older post as still-causal.
Posts to understand this · as of Nov 8
Instantly is a cold-email platform for finding leads, managing inboxes and running outbound campaigns.
Instantly’s share peaked in June, dropped sharply in July, then rebuilt from September through October; the last 30 days are up 31.7%. The posts point to recurring outbound work rather than a launch: Claude Code hooks, agent-managed replies across roughly 200 mailboxes, and a hiring request for domain warming expertise. That gives the recovery a practical operations thread.
Posts to understand this · as of Nov 7
OpenRouter is one API for accessing, routing and paying for models from many providers.
OpenRouter's August spike receded in September, and its last 30 days are essentially flat at +0.2%; the supplied posts do not explain the August jump. Stripe's November 10 announcement that OpenRouter is now part of Stripe gives the partial November bar concrete context. Alongside a Krea promotion and September's OpenAI spending crossover, the news centers on model access and economics.
Posts to understand this
Substack is a publishing platform for newsletters, podcasts and paid creator subscriptions.
Substack's share hit 1.03% in May, nearly halved in June, bounced to 0.79% in July, then slid to 0.49% in October. The notable posts came at the end of May and July, from Tom Orbach and Elena Verna, and Tyler Denk questioned its network effects in late October. The last 30 days are up 6.8%, but that rests on a few November days.
Posts to understand this · as of Nov 4
 inCreator lessonsElena Verna shared lessons from building audiences on LinkedIn and SubstackTO
 inRising newsletterTom Orbach reached #1 rising business newsletter on Substack, above Lenny and Prof GTD
 inNetwork effects doubtTyler Denk asked if Substack's network effects are dying, citing Emily Sundberg's flat growth
Semrush is an SEO and content platform for search research, competitive analysis and AI visibility.
Semrush’s May partnership with Lovable coincided with a climb toward June’s high, although the posts do not establish what drove that peak. Share fell sharply through August, then recovered modestly, with the last 30 days up 2.1%. September’s reassurance about Google redirects and October’s Spotlight discussion of buyer questions show continued attention to search data reliability and AI visibility.
Posts to understand this
Canva is a visual design platform for creating graphics, presentations, video and other marketing assets.
Canva’s April high coincided with Canva Create announcements, but share declined through most of the following months despite May’s Grok connector launch. October brought a recovery, and the last 30 days are up 30.3%. November’s post about Canva’s layoff package adds a different source of attention: employee support, rather than another product release.
Posts to understand this
Ahrefs is an SEO platform for keyword research, backlinks, rank tracking and AI visibility.
Ahrefs’ May spike gave way to a lower band of conversation through October; share is down another 34.1% over the last 30 days. The posts do not explain May’s surge, but show competing pressures afterward: claims that AI tools replace SEO dashboards, Google redirects disrupting data, and a practical Ahrefs-to-Claude workflow that keeps the audit useful.
Posts to understand this
Zapier connects applications and automates work through triggers, actions and AI agents.
Zapier’s May high gave way to a broader decline, interrupted by an August bounce; the last 30 days are essentially flat. The posts center on agents connected to operational workflows, from GTM automation to Zapier’s October SpaceX Super Intelligence partnership. That launch adds a concrete integration story, but the curve shows no renewed rise yet.
Posts to understand this · as of Nov 7
ZoomInfo provides B2B contact, company and intent data for sales and marketing teams.
ZoomInfo’s June high gave way to three months of declines before October’s rebound; share is now up 15.5% over the last 30 days. The posts point to recurring pressure rather than one event: Ava 2.0 pitched replacing ZoomInfo, layoffs drew scrutiny, and October’s $27/month Moltsets launch renewed the argument over contact-data pricing.
Posts to understand this
Profound measures and improves how brands appear in AI answers.
Profound’s curve is uneven rather than sustained: September’s rebound softened in October, and share is down 28.3% over the last 30 days. The posts show recurring tension between adoption and scrutiny, from criticism of content quality and sampling reliability to inclusion in a practical AI-search workflow. No single event explains the swings.
Posts to understand this
ElevenLabs provides voice models and agents for speech, dubbing and conversational AI.
ElevenLabs climbed from its August low to an October high, with September posts about reported $600 million-plus ARR and enterprise hiring, followed by Adobe’s promotion of v4 in Firefly. Those give the rise concrete commercial and product context. Share is down 16.4% over the last 30 days but up 19.2% over 90, so the recent cooling follows a broader gain.
Posts to understand this
Attio is a flexible CRM with a database-style model, automation and agent access.
Attio’s May high coincided with its GTM Atlas launch, followed by a slide through September and an October rebound. The last 30 days are effectively flat at +0.8%, so that rebound has not become a sustained climb. The posts shift from an AI GTM resource to positioning criticism and praise for competitor migration links, with no single event explaining the decline.
Posts to understand this
Apollo.io combines a B2B contact database, sales engagement tools and AI-assisted prospecting.
Apollo.io peaked in May, as operators showed how to run it from inside Claude with Apollo as the data layer. Share has slid since, and the last 30 days are down 38%. ApolloNext's AI GTM system launch on September 30 gave the brand a new story, but October still came in lower.
Posts to understand this · as of Nov 4
 inClaude workflowRaouf Lemouchi stopped opening Apollo and ran prospecting through Claude instead.BR
 inSkill giveawayBrigitta Ruha packages Apollo prospecting, enrichment and sequences into one Claude skill file.TS
 inEvent recapTom Slocum recaps ApolloNext, where Apollo unveiled three products for its AI GTM system.
Apify provides ready-made web scrapers and cloud infrastructure for collecting web data.
Apify held an elevated share from May through July before three months of decline; the last 30 days show a 48.1% recovery. June posts place it inside Claude MCP setups and LinkedIn prospecting workflows, while October’s pitch emphasizes tools for AI agents. The recurring thread is practical tool access, with no single documented launch to explain the rebound.
Posts to understand this
Granola is an AI meeting notepad that turns rough notes and transcripts into useful summaries.
Granola’s share peaked in May, fell through July, and recovered unevenly into October; the latest 30 days are up 15.7%. The October 29 voice typing launch adds context, but does not establish what caused October’s rebound. Recent posts show Ashley Lewin dropping Wispr because Granola already owned her meeting habit, and Sauna using Granola alongside email and calendar data.
Posts to understand this
HeyReach automates LinkedIn outreach across multiple sender accounts and a shared inbox.
HeyReach recovered in October after a summer slide, with conversation share up 111.3% over the last 30 days. The posts establish two recurring themes: LinkedIn platform risk and automated campaign setup through Alysio. Both date to March, so neither explains the recent jump; the evidence supports that tension, rather than a specific new catalyst.
Posts to understand this
RB2B identifies the people and companies visiting a website so sales can follow up.
RB2B’s share recovered in September and October after an August low, and is up 90.6% over the last 30 days. The November 2 team statement reporting Adam Robinson’s death, alongside his family, and personal tributes provide a clear catalyst for recent attention. These posts center on grief, friendship and his public presence as a founder.
Posts to understand this
Intercom is a customer messaging platform built around Fin, its AI support agent.
Intercom’s sharp June spike lines up with Salesforce’s announced agreement to acquire Fin. Share dropped in July and stayed well below June through October, with a further 14.3% decline over the last 30 days. The evidence points to a deal-centered burst: Fin’s observability launch preceded it, and November commentary revisits Salesforce’s acquisition strategy.
Posts to understand this
LangChain provides open-source frameworks and managed infrastructure for building stateful AI agents.
LangChain held a fairly steady share from June through September, with conversation spanning open-source agent infrastructure and Harrison Chase’s account of a late gateway launch. October’s lower share and a 37.4% decline over the last 30 days show softer attention; Nimble’s news-agent guide supplies a practical use case, but no single post explains the drop.
Posts to understand this · as of Nov 4
Baseten deploys and runs custom AI models in production.
Baseten’s summer rise reached its highest monthly share in August, when it made Inference Engineering free to read. Attention then declined through October, with share down 25.9% over the last 30 days. Harvey’s M&A diligence work and CodeRabbit’s NVIDIA spotlight supplied concrete follow-on stories, but those partnerships did not sustain the summer level of conversation.
Posts to understand this
Nooks is a sales workspace for parallel dialing, prospecting, coaching and AI-assisted outreach.
Nooks rose steadily from April through July, dropped sharply in August, then recovered unevenly; its current direction is up 18.5% over the last 30 days. November’s Node announcement supplies a concrete new product hook, while Replit’s use of Nooks provides a customer proof point. Peter Mollins’ August departure post recaps growth but does not explain that month’s drop.
Posts to understand this
Common Room turns buyer signals from communities and the web into prioritized sales opportunities.
Common Room’s rise from April through July culminated alongside Zoom’s July 2 acquisition announcement, then dropped sharply in August and September. Conversation share remains down 11.9% over the last 30 days. Later posts discuss GTM consolidation and Zoom-based call intelligence, a narrower follow-through than the acquisition moment; they do not explain the earlier buildup on their own.
Posts to understand this · as of Nov 3
 inProduct follow-throughCommon Room links Zoom transcription accuracy to sales coaching and deal reviewsFT
 inAcquisition reactionFormer employee Florin Tatulea congratulates Common Room on its Zoom acquisitionND
 inConsolidation thesisNico Druelle places Common Room among acquired GTM platform challengers
Exa.ai is a web search API designed for models and AI agents.
Exa sat between 0.3% and 0.5% for six months, then reached 0.7% in October after Exa 3.0 launched with claims of first place on every benchmark it tested. A GTMnow interview on its run to $100M ARR followed, and Parallel benchmarked against it days later. The 30-day move is up 47.1%.
Posts to understand this · as of Nov 4
Warmly identifies website visitors and uses AI agents to start sales conversations.
Warmly’s climb through July culminated in discussion of its acquisition by HubSpot alongside Common Room’s sale to Zoom. Share fell sharply in August and declined through October; later commentary revisited those deals as evidence of consolidation rather than a fresh Warmly event. The last 30 days are down 58.8%, extending that loss of attention.
Posts to understand this
OpenCode is an open-source coding agent that works with cloud and local models.
OpenCode’s share built through August, then eased in September and October; the last 30 days show a modest 4.9% lift. No supplied post explains the August high. The recurring pattern is inclusion in other products’ workflows, from Linear’s issue handoff and Higgsfield’s CLI compatibility to Figma’s October MCP partner announcement.
Posts to understand this · as of Nov 8
Gamma turns prompts into presentations, documents, websites and images.
Gamma’s May high coincided with Grok’s connector announcement, followed by a July trough and an uneven recovery through October. The Claude workflow example shows the same recurring hook: decks created inside another AI tool. Gamma 5 added an October launch moment, but the last 30 days are down 16.5%, so that recovery has not held.
Posts to understand this
AirOps helps content teams measure AI visibility and build workflows to improve it.
AirOps’ May spike followed its April Anthropic collaboration announcement, then settled into a much lower July-to-September band. October recovered, and share is up 35.3% over the last 30 days. Recent posts shift the discussion from content volume toward citation research and measurement, although EasyVista’s example pairs AirOps content operations with Peec AI for visibility tracking.
Posts to understand this
1mind provides AI sales agents for websites, demos, live calls and customer success.
1mind rose through June, lost ground through September, then rebounded in October; share is up 76.3% over the last 30 days despite a weaker 90-day picture. Its October summit provides a concrete occasion for renewed discussion, though the posts cannot establish it as the sole cause. Earlier evidence centers on buyer use of its agent and a marketing hire.
Posts to understand this
Firecrawl turns websites into clean, structured data for models and agents.
Firecrawl’s curve is choppy, with a July high followed by softer August and September shares, then an October recovery; the last 30 days are up 38.4%. July’s credit incentives and November’s competitor-research workflow offer distinct conversation hooks, while the earlier Lovable connector shows a recurring pattern of Firecrawl appearing inside broader tool stacks.
Posts to understand this · as of Nov 6
Higgsfield generates video and images for ads and social content.
Higgsfield rose into a June-July plateau, dipped in August and recovered through October; its last 30 days are up 11.3%. The posts span creator use, Together AI infrastructure and the November Miracle private beta, rather than one event that explains the whole curve. Miracle adds a concrete new topic: localized video editing, with access through Higgsfield MCP promised next.
Posts to understand this
Grok Bot is an always-on agent that learns routines and completes work across existing software.
Grok Bot entered the conversation with its August early beta, then gained share each full month through October; the last 30 days are up 38.2%. The launch centered on work across existing tools, including vendor negotiations, support and CRM updates. October integrations from Runway and Krea added creative uses, giving the conversation fresh material beyond the initial launch.
Posts to understand this
Claudeforce brings Salesforce customer context and actions into Claude through Salesforce and Anthropic's partnership.
Claudeforce appeared in August with the announcement that Claude would run natively on Salesforce, then gained share during September’s Dreamforce discussion. October’s headless software comparison shows the topic moving into practical evaluation, but share fell sharply from September. The last 30 days are down 71.3%, consistent with a launch-and-conference burst that has faded.
Posts to understand this
GPT-6 is OpenAI's frontier model line, tracked as the conversation about its releases, its evals and early use.
GPT-6 went from almost nothing to 5.1% in September as Astra's first evals landed: Perplexity scored it highest on wandr, and Peter Walker saw OpenAI take 31% of OpenRouter spend. Share fell to 1.7% in October and is down 59.3% over 30 days. Now it often appears as the mark others get measured against, as in Cognition's Gemini 4 evals.
Posts to understand this · as of Nov 4
Claude Fable is Anthropic's frontier Claude model line, tracked as the conversation about its releases and what people build on it.
Fable’s June availability on Databricks preceded a July conversation peak, followed by an uneven decline through October. The November 9 launch of Fable 5.2 and its arrival in Viktor put releases and real-work benchmarks back in focus, alongside a 30.7% rise over the last 30 days, though conversation remains below summer levels.
Posts to understand this
GPT-5 is OpenAI's flagship closed model family, offered as a hosted API across tiers rather than an open, self-hosted release.
GPT-5 fell sharply after April and stayed in a narrow, low range from May through October. The posts show a recurring comparison role: a benchmark reference, a cheaper Mini deployment at Tampa General Hospital, and a complaint about frontier pricing. Share is up 43.8% over the last 30 days, but no single supplied event explains that move.
Posts to understand this
Claude Opus is Anthropic's top-tier model, built for buyers weighing closed frontier power against cheaper open alternatives.
Claude Opus conversation has seesawed: July and September rebounds coincided with Notion adding Opus 5 and the Opus 5.5 announcement, with dips in June and August. Share fell again in October and is down 21.7% over the last 30 days; Simular’s October comparison puts cheaper open models against Opus on computer-use performance and cost.
Posts to understand this
Grok 4 is xAI's frontier language model powering the Grok assistant and developer API.
Grok 4 jumped in July, when Genspark added Grok 4.5, then lost share each month through October. September’s Grok 4.7 teaser and an October benchmark endorsement show continued release and performance discussion, but neither sustained the summer level. The last 30 days are down 77.3%; these posts do not establish one cause for the July spike.
Posts to understand this
Claude Sonnet is Anthropic's mid-tier AI model, built for coding, agents and everyday work at lower cost than its top-tier sibling.
Sonnet’s June spike coincided with the Sonnet 5 launch and its arrival in Perplexity, followed by a retreat through August despite permanent introductory pricing. The September 5.5 announcement accompanied a smaller rebound that held roughly steady in October. Share is down 53% over the last 30 days, so the release cycle has not sustained attention.
Posts to understand this
Muse Spark is Meta's AI model for running coding and other agents.
Muse Spark’s share rose each month from July through October, and the last 30 days are up 153.5%. The evidence points to repeated technical scrutiny rather than one launch: Cline’s agent-harness experiment, a VulcanBench comparison and Sudo L7 results. Successive tests of Muse Spark 1.2 and 1.3 give the sustained rise a concrete pattern.
Posts to understand this
Gemini Flash is Google's fast, low-cost model line, built for high-volume API work and coding.
Gemini Flash’s May spike aligns with the 3.5 Flash release and Databricks availability; the supplied posts do not explain July’s second surge. Share then declined through October despite September’s Wiz partnership, with a modest 4.3% lift over the last 30 days. The later evidence shifts from launch access to concrete security applications and Remote’s accuracy-versus-cost comparison.
Posts to understand this
Kimi is Moonshot AI's open-weight model line, used for long-context work and coding.
Kimi’s July spike to 2.6% share coincided with K3 coding comparisons: Together AI claimed Claude Fable 5 performance at roughly 35% of the price, while another post highlighted its frontend ranking. Share faded through September before an October uptick. The last 30 days are up 83.1%, with Arena’s October 23 model teaser providing a fresh hook.
Posts to understand this · as of Nov 9
Qwen is Alibaba's open-weight model family, widely used for local and self-hosted deployments.
Qwen's August spike gave way to lower share in September and October, even as Qwen-Image-2.1 and Qwen3.8 Max Prime appeared in posts. The evidence does not explain the August jump; it shows a recurring cost-and-capability pitch across search, images, and model access. The last 30 days are up 9.8%, a modest recovery after that retreat.
Posts to understand this · as of Nov 8
GLM is Z.ai's open-weight model line, used for coding and vision work at low cost.
GLM went from almost nothing in May to about 0.65% in June, then held through a 0.72% August high. The story since is cheap, practical use: Bolt users put GLM 5.3 Flash first, and You.com added GLM 5.3 to its router. Attention is cooling anyway, with the last 30 days down 36%.
Posts to understand this · as of Nov 4
Mythos is Anthropic's frontier model line, built for advanced reasoning and agentic work.
Mythos attention spiked in April and June, then stayed low from July through October. The latest conversation pairs the November 5.2 launch and coverage of its coding and cybersecurity capabilities with GitLab’s October integration of Mythos 5.1 for remediation. Share rose 147% over the last 30 days, while remaining down 64% over 90 days.
Posts to understand this
 XLaunchClaude introduces Mythos 5.2 with coding, reasoning, and vision improvementsCR
 XRelease coverageConstellation Research reports Mythos 5.2 release and coding and cybersecurity capabilitiesG
 inDeploymentGitLab integrates Mythos 5.1 to connect vulnerability discovery, fixes, and policy enforcement
Midjourney is an AI image generator known for stylized, painterly visuals used across creative and marketing work.
Midjourney’s June spike sits alongside two distinct conversations: its community-funded business model and Gamma’s use of its image tools for an entire brand system. Neither post identifies a launch that explains the jump. Share settled much lower in July and August, declined through October, and is down another 40.7% over the last 30 days.
Posts to understand this
Devin is Cognition's autonomous AI software engineer that writes, tests and ships code from a natural-language prompt.
Devin’s curve is uneven: attention fell after April’s Windsurf 2.0 announcement, recovered through August, then dipped in September. October’s Pylon integration supplied a concrete new use case: hand customer bugs to Devin and track fixes inside support. Share is up 45.6% over the last 30 days, consistent with that renewed workflow discussion.
Posts to understand this
Runway is an AI platform for generating and editing video and images.
Runway’s September spike gave way to a lower October, with conversation share down 26% over the last 30 days. The posts do not identify a September catalyst: they span a solo creator’s ad, Pika’s price comparison and October praise for 60 Minutes coverage. That mix suggests recurring attention across creative work, cost and employment, without a documented event to explain the spike.
Posts to understand this · as of Nov 6
Jev is TypeSafe AI's decision model, which returns typed answers such as choices, probabilities and scores instead of text.
Jev’s September debut centered on TypeSafe’s decision model and LangChain’s comparison with LLM judges, which fits its sudden jump from zero conversation share. October’s Parallel Decisions API added web grounding, but the launch burst faded: share roughly halved in October, and the last 30 days are down 63%.
Posts to understand this · as of Nov 4
Muse is Meta's personal AI agent, which connects to a person's email, calendar and payments to shop, book and schedule for them.
Muse went from almost no conversation in August to 1.2% in September, alongside Replit app creation and Klaviyo’s small-business launch partnership. That concentration of new capabilities fits the September spike. Share fell to 0.9% in October and is down 57.9% over the last 30 days, with later evidence focused on audience demographics.
Posts to understand this · as of Nov 9
Instinct is a personal AI agent with its own email address that creates accounts, contacts businesses and handles support requests for its user.
Instinct first showed up in August, jumped to 0.8% in September and reached 1.0% in October. October's posts show it named as a partner on Meta and Sierra's personal agent protocol, then Peter Walker questioning the rush around its jump from $100M to $30B. Share is down 25.7% over the last 30 days.
Posts to understand this · as of Nov 4
Muse Wonder is Meta's most capable model series, built for personal and work agents that keep track of goals across long tasks, including coding.
Muse Wonder entered the conversation in October after six months with no recorded share. Genspark availability on October 14 and Cursor support the next day provide a clear launch cluster, followed by Cognition’s benchmark comparison later that month. The last 30 days register as new, so this is an arrival story with limited evidence about staying power.
Posts to understand this · as of Nov 7
Claude Duet is Anthropic's personal AI agent app for proactively handling tasks and automating work across connected apps.
Claude Duet entered the conversation in October after six months with no recorded share, and its last-30-day status is new. The October 21–22 partner announcements explain that arrival: Stripe covered payments and refunds, Docusign covered agreements, and Zapier connected automations across apps. This is a launch-shaped curve, with too little history to establish staying power.
Posts to understand this · as of Nov 5
Braze is a customer engagement platform for creating personalized marketing campaigns across email, mobile, web and other channels.
Braze’s October jump breaks sharply from six months of low conversation share, with the last 30 days up 350.9%. Its October 20 agreement to be acquired by Salesforce supplies the clear catalyst, followed by debate about customer implications and Bloomreach’s competitive position. June’s OfferFit discussion supplies earlier context for consolidation around AI decisioning.
Posts to understand this
dots is OpenAI's always-on personal agent, which uses its own cloud computer and connected apps to complete tasks for its user.
dots first appears in September and expands sharply in October, alongside concrete demonstrations: HeyGen’s lesson videos and John Barrows’ daily prospecting workflow. Liza Adams adds caution about personal agents acting with sensitive information and imperfect judgment. Share is down 33.1% over the last 30 days, so that initial burst has cooled without a single documented cause.
Posts to understand this
Passionfroot is a creator marketing platform that helps brands find creators and manage sponsorships and partnerships.
Passionfroot’s small July appearance coincided with its Series A and a customer endorsement, but that attention faded by September. October’s larger spike coincided with its participation in Kyle Poyar and Maja Voje’s GTM report, linking creators to AEO, founder content and launches. The last 30 days are up 406.7%, off a small base.
Posts to understand this · as of Nov 3
Join 19,836+ GTM leaders and practitioners. Free, unsub anytime.
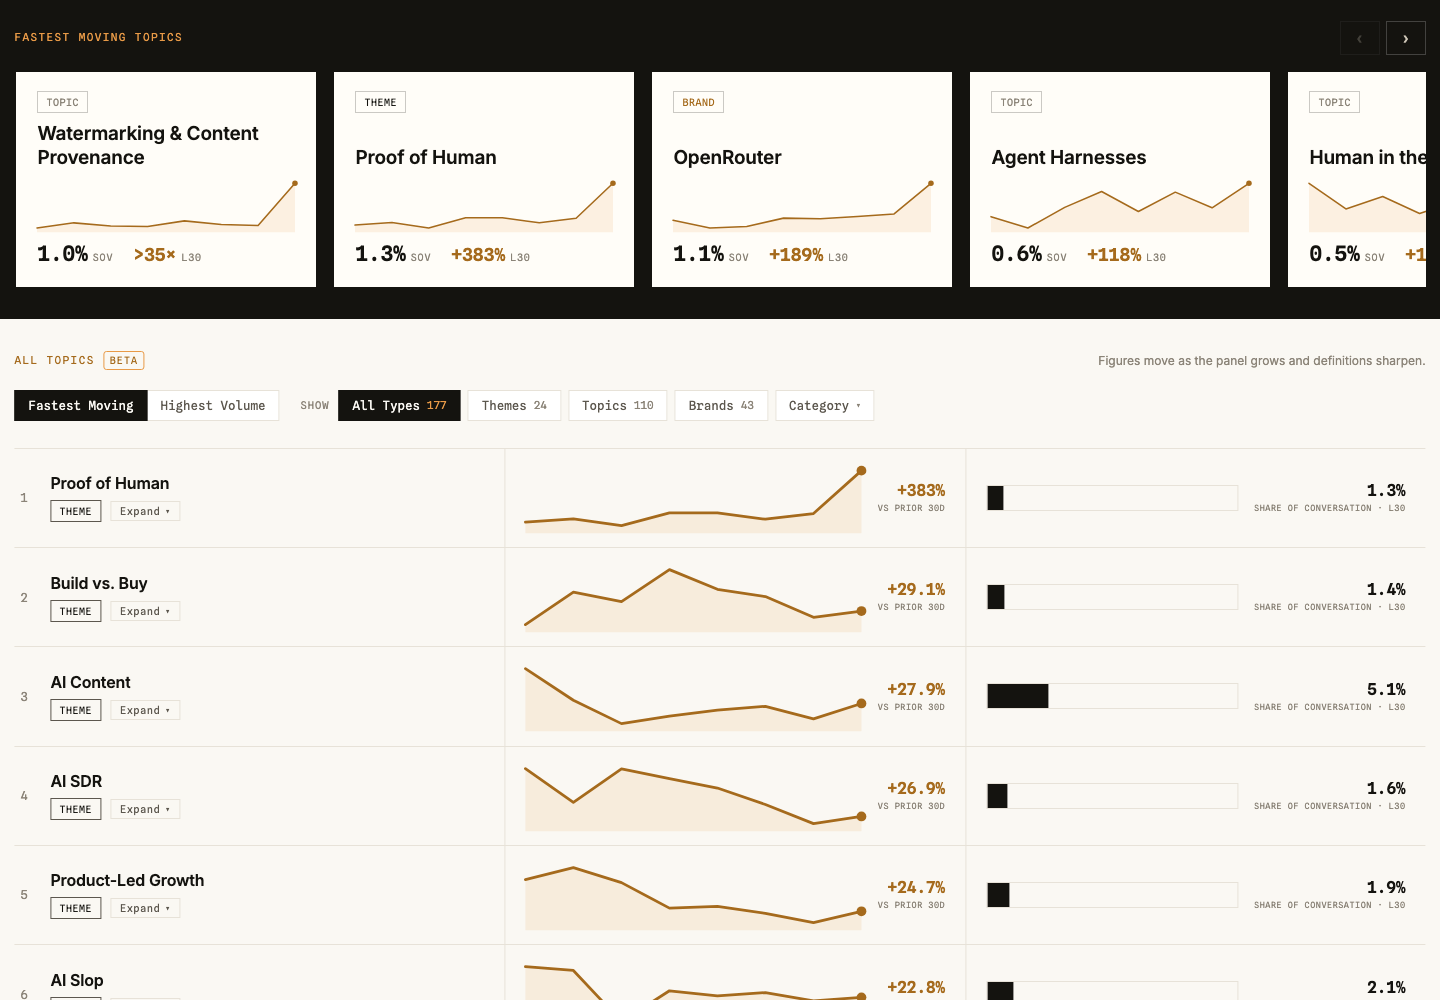
Loading people…
join 19,836+ gtm leaders, unsub anytime.
Hi, I'm Adam. I'm an independent builder & industry analyst. My goal is to help GTM leaders make sharp decisions in uncertain markets.
This is the methodology for my GTM Market Tracker — the score, the rankings, and the category maps.
Topics measure what the GTM conversation is actually about, at two grains.
Clusters are built from topics, so both appear in one ranked list.
The volume and change measures are both variations on Share of Voice (SOV). The volume is a count of posts fitting the topic or theme, engagement weighted. The denominator is every panel post that matched at least one maintained topic.
Shares do not add up to 100%. A post about coding agents inside GTM engineering is about both, so it counts for both — the number is prevalence, not a slice of a pie.
Beta. These figures move as the panel grows and the definitions sharpen. Every published number carries the registry version it was measured under, and when a change reprices the board I say so in that issue's notes.
I cover products and companies with a central application for B2B go-to-market in the AI era. Most are sales- or marketing-focused (e.g. Gong, Clay), but I also cover broader solutions that are clearly GTM-relevant (e.g. Claude Code, Vercel, Exa).
On the edges my judgment determines what fits (and what doesn't). Like all things, this evolves as I learn and as the market changes.
Brand's share of panel conversation, normalized 0–99 against the field.
My scores are a share-of-voice (SOV) measure, not a rating of the product capabilities. I am not scoring whether a product is good or best. I'm measuring how much it shows up in the GTM conversation. This a useful concept to understand market trends, but isn't a buyer score alone.
Here's how it works:
| Window | What it answers | |
|---|---|---|
| SOV Score | Last 90 days | Where does this brand stand right now? |
| 60-day move | Last 60 days vs the 60 before them | Which direction is it heading? |
The move is a percentage change in share of panel conversation — the brand's share over the last 60 days against its share over the 60 days before that. Both are recalculated nightly, against the panel as it stands that night. The move window ends two days back, because the most recent day or two of collection is still filling in. Scores you see today are as of 2026-11-12.
A voice is a source on the curated panel. It's a person or a publication whose GTM commentary I've chosen to track, across LinkedIn, X, newsletters, blogs and podcasts. It is a carefully curated list or experts and operators, not a crawl of the internet. I have three rules for reading the panel.
Brands sit inside Markets. These are my framework for grouping companies by the AI era "races" and don't necessarily align to traditional industry categories. Two different things can be true of a brand at once:
My highest level organizing framework has a strong bend toward AI. I believe the traditional categorization is breaking down quickly. This is how I see the space at a high level:
| Type | Definition | Examples |
|---|---|---|
| Coding Agents & Experience Builders | AI coding assistants and app builders. | Claude Code, Cursor, Lovable |
| Orchestration | The workflow layer that wires data, agents, and apps into GTM systems. | Clay, Zapier, n8n |
| Agent-Native GTM | Software where agents are core and do the work — purpose-built for GTM jobs. | 11x, Artisan, Attio |
| GTM Developer Tools | The API- and MCP-first primitives used to build and run agent-based GTM systems. | Exa, Vercel, ElevenLabs |
| SaaS for GTM | The GTM application layer — multi-feature software you operate for sales, marketing and CS. Many are going headless and shipping agents. | Salesforce, HubSpot, Gong |
| Creative & Content | AI generation of media assets — images, video, decks, avatars, copy. | Canva, Runway, HeyGen |
| AEO | Platforms that help brands measure & optimize visibility inside AI answers. | Profound, Scrunch AI, AthenaHQ |
| GTM Adjacent | Broad, general-purpose platforms a company runs on (comms, docs, cloud, data) — used by GTM but orthogonal to sales and marketing execution. | Slack, Notion, Snowflake |
Categories are generally organized around use cases, go-to-market motions, or the intersection of the two. That said, there is a balance of many factors in this framework and it ultimately comes down to my judgment.
| Category | Definition | Examples |
|---|---|---|
| GTM Developer Tools | Broad dev primitives GTM teams run through agents and APIs. | Exa, Vercel, Twilio |
| Data & Intelligence | Enrichment, intent, and signal data that feeds the pipeline. | Clay, ZoomInfo, Apollo |
| Selling | Active deal execution — conversation intelligence, coaching, proposals, demos. | Gong, Salesforce, Granola |
| Marketing Execution | Campaigns, content, ABM, and marketing ops. | HubSpot, Klaviyo, Customer.io |
| Advertising | Paid-media execution and measurement — DSPs, paid social and search, attribution. | The Trade Desk, LiveRamp, Metadata |
| Creative & Content | AI generation of GTM media — video, images, decks, avatars, copy. | Canva, Runway, HeyGen |
| GTM Infrastructure | GTM-specific pipes — email deliverability, CDP and reverse-ETL, billing. | Hightouch, Metronome, Paddle |
| Website & Inbound | Websites, chat, and inbound capture that convert traffic into pipeline. | Webflow, Chili Piper, Framer |
| AEO | Visibility inside AI-generated answers. | Profound, Scrunch AI, AthenaHQ |
| Prospecting | Outbound — finding, qualifying, and reaching buyers. | Outreach, Salesloft, Nooks |
| Customer Success | Post-sale onboarding, retention, and expansion. | Intercom (Fin), Gainsight, Zendesk |
| Autonomous CRM | AI-native CRMs that run pipeline, deals, and relationships themselves. | Attio, Day.ai, Clarify |
Products can fit types and multiple categories, but there must be a strong case.
I score Agent Readiness as a secondary factor, but it matters: in an agent era, whether your systems can actually build on a product matters more than its UI. It's an analyst-judged 0–99 score (with an A–F grade) across four surfaces — API, MCP server, SDK, and CLI — plus the quality of the docs behind them. Multiple agents, each with a different persona, assess those surfaces and docs; the Surfaces column shows exactly which a product ships.
The index covers people whose professional work is relevant to GTM, including sales, marketing, growth and the AI tools shaping that work. Ranking requires at least 5 eligible authored LinkedIn posts in a trailing 90 day window. We count authored posts from vendor voices; for other creators, posts must relate to GTM. We publish the top 200 GTM Practitioners & Creators and top 150 GTM Tech Vendor Voices by score. The "Scored" count shows the published creators in each category; "Tracked" includes the broader coverage roster.
Scores compare each creator with the full field, on a scale up to 99. The same weights apply across both categories.
| Component | Weight |
|---|---|
| Average engagement per post | 30% |
| Total engagement | 30% |
| Known audience | 40% |
Engagement combines reactions, comments and reposts. Known audience combines LinkedIn followers and verified newsletter subscriber counts.
GTM Practitioners & Creators do or teach GTM work, including GTM practitioners at horizontal AI companies. GTM Tech Vendor Voices are founders, leaders and employees of core GTM technology vendors in the Tech Index.
Send any suggestions or issues to adam at adamgtm.com. I verify them, write the fix back to the system and publish.
If you're building something interesting in this space, but it's not covered yet, please suggest a product here.
Building or running a product that belongs in the GTM Index? Tell us about it. We review every submission and add the ones that fit.
join 19,836+ gtm leaders, unsub anytime.